The French Debt Spiral and the Fall of the Continental Premium: A Sovereign FIRE Guide to Hedging and Geographic Arbitrage
A structural deconstruction of the French sovereign debt impasse and institutional decay, detailing an actionable blueprint for capital defense, Ireland-domiciled UCITS architecture, and low-drag geographic arbitrage.

Executive Summary: By autumn 2026, French public debt has climbed to €3.6 trillion (119% of GDP), the fiscal deficit lingers at 5.4%, and ten-year sovereign bond yields are testing two-decade highs near 5%. Street unrest and an intractable budgetary stalemate signal the definitive curtain call for the Continental European welfare model. For those pursuing Financial Independence, Retire Early (FIRE), this turmoil is not spectator sport. It is a critical macro signal to re-underwrite capital margins of safety, erect institutional firewalls, and execute deliberate geographic arbitrage.
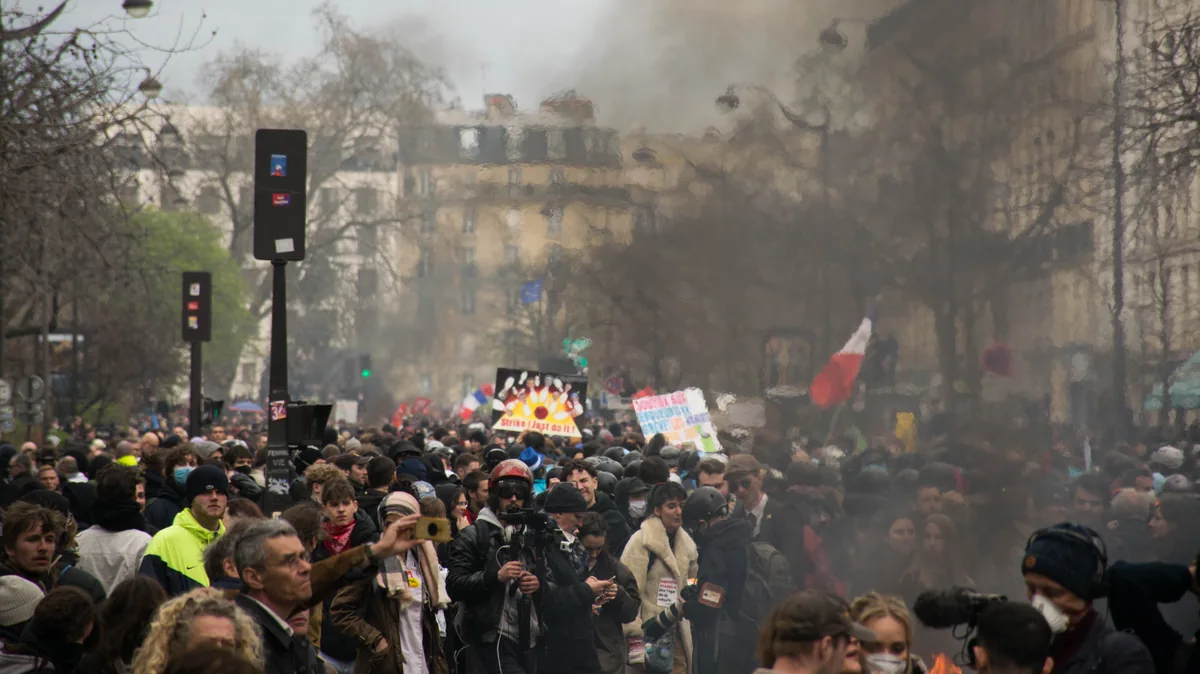
Figure 1: Riot forces and demonstrators face off in Paris, capturing the structural deadlock between Continental welfare entitlements and sovereign solvency.
I. The Blunt Knife Behind the Barricades: Three Vectors of Macro Contagion
Public perception fixes on burned cars, shattered storefronts, and paralyzed transport networks. In the cold ledgers of global capital, however, physical damage is mere surface friction. The real qualitative shift lies in the credit repricing of a core European sovereign and the resulting rerouting of cross-border capital flows.
| Transmission Vector | Primary Catalyst & Mechanics | Deep Capital & Asset-Side Impact |
|---|---|---|
| Sovereign Spreads & Bond Derating | Street resistance to austerity paralyzes the legislature. The OAT-Bund spread widens continuously, with French ten-year borrowing costs crossing into Greek and Italian territory. | Europe’s second-largest economy loses its capacity for organic fiscal repair. Eurozone assets absorb a permanent “political risk discount,” accelerating capital repatriation by institutional allocators and Japanese life insurers. |
| Critical Mineral Supply Chokepoints | Social friction cascades to strategic overseas territories. Unrest in New Caledonia—source of 5.6% of global nickel production—halts extraction at Eramet-backed facilities. | Class-1 nickel and nickel sulfate spike on the LME, immediately exposing the fragility of ternary lithium battery and clean-tech supply chains through cost-push inflation. |
| Institutional Tax Drag & Insurability | Over 80% of businesses surveyed by MEDEF report long-term pessimism; compulsory commercial riot insurance surcharges are codified into law. | Surging reinsurance premiums across Continental operations trigger an exodus of engineers, founders, and high-net-worth capital toward jurisdictions with statutory predictability. |
When an entitlement state’s welfare promises outstrip its underlying industrial productivity, the default political reflex is to expand transfer payments and postpone reform. The bill is ultimately settled through only two mechanisms: predatory levies on accumulated wealth and the stealth dilution of fiat purchasing power. This dynamic is a direct warning to anyone living off deployed capital.
II. Excising Continental Exposure: Asset-Side Defense for FIRE Portfolios
Facing predatory taxation and currency debasement in over-leveraged states, an independent balance sheet must never share a single point of failure with an insolvent sovereign. Capital defense begins by anchoring wealth strictly to productive, global economic capacity.
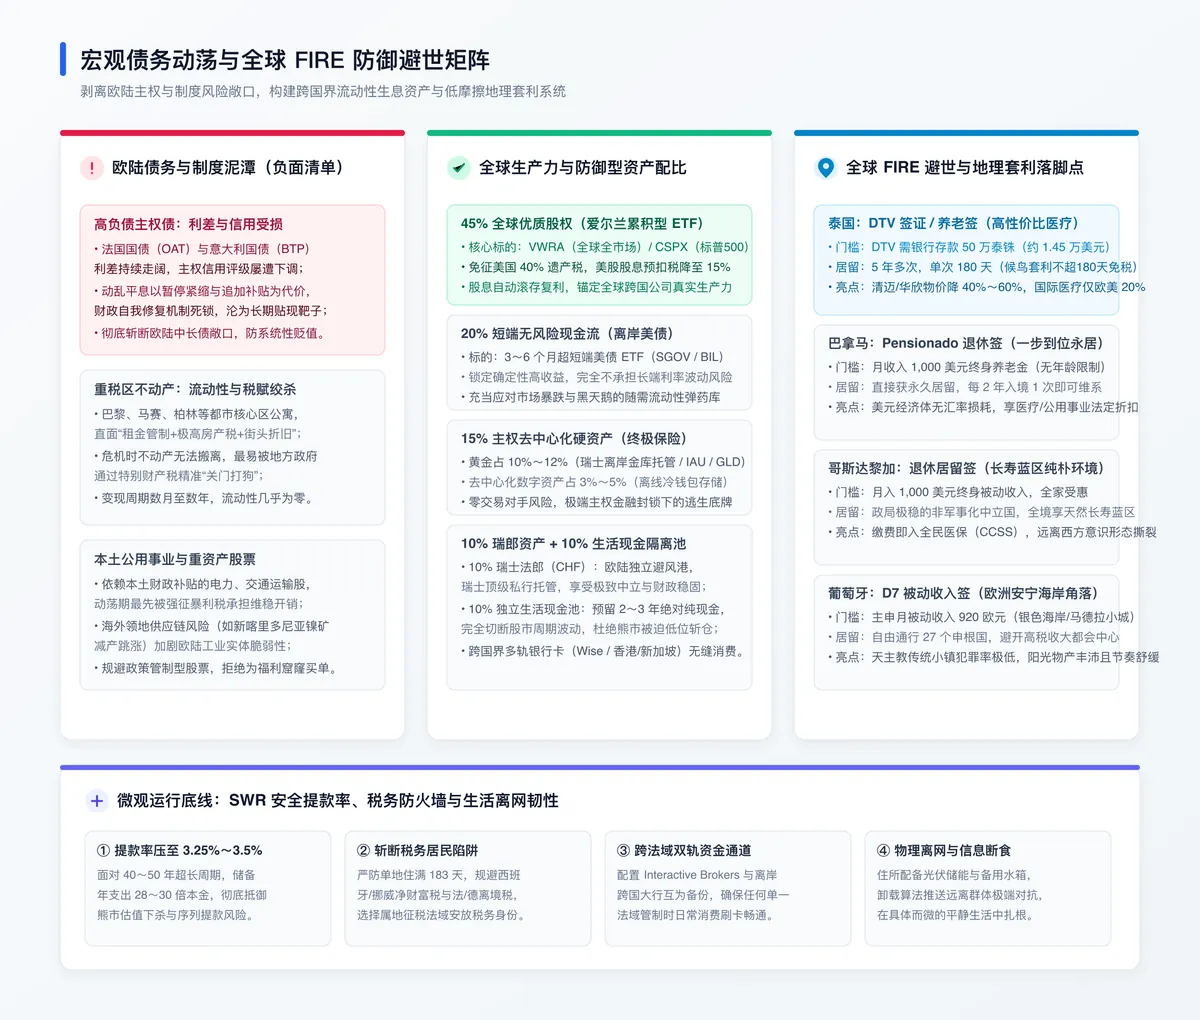
Figure 2: Defensive asset allocation, institutional structuring, and geographic arbitrage matrix under sovereign debt distress.
1. The Portfolio Exclusion List: Assets to Amputate Immediately
- Long-Duration High-Debt Sovereign Debt: Liquidate exposure to French OATs, Italian BTPs, and blended long-duration euro sovereign paper. Their nominal coupons offer zero margin of safety against structural spread widening and persistent re-inflation.
- Heavy-Tax Continental Real Estate: Prime residential holdings in Paris, Berlin, or Marseille are trapped in a regulatory vice: strict rent caps, escalating municipal property taxes, and aggressive exit taxes on capital gains. As detailed in our analysis on Asset Liquidity and Downside Defense Strategies, illiquid property requires months or years to exit, cannot be moved across borders, and forms the easiest target for predatory municipal balance-sheet repair.
- Subsidy-Dependent Domestic Utilities: National rail, regulated grid operators, and legacy telecom incumbents are routinely subjected to emergency price freezes and windfall clawbacks during civil crises, negating their defensive dividend profile.
2. The Resilient FIRE Allocation Model: Anchored in Productivity and Liquidity
To generate durable passive cash flows that survive sovereign debt cycles, consider the following baseline asset allocation:
The Sovereign-Resilient FIRE Allocation Matrix
- 45% Global Productive Equities (USD-Denominated): Core holding in an All-World equity ETF, capturing multinational enterprises protected by wide economic moats and geographically diversified free cash flows.
- 20% Short-Duration Risk-Free Paper: Ultra-short US Treasury ETFs (such as SGOV or BIL) or offshore dollar cash equivalents, capturing risk-free yield while preserving dry powder for systemic liquidity dislocations.
- 15% Sovereign-Neutral Hard Assets: Physical gold (10%–12%, secured via non-bank offshore vaults or non-leveraged physical trust ETFs, eliminating counterparty friction); decentralized digital assets (3%–5%, held exclusively in cold storage across air-gapped devices as an emergency off-ramp against capital controls).
- 10% Swiss Franc Holdings (CHF): Direct exposure to a multi-century tradition of fiscal sobriety and jurisdictional neutrality, hedging Eurozone monetary fragility.
- 10% Independent Liquidity Buffer: Two to three years of baseline living expenses held in unencumbered cash. This decouples daily survival from cyclical asset downturns, eliminating the need to liquidate shares during market drawdowns—a core risk outlined in our S&P 500 Dollar-Cost Averaging Playbook.
3. Structural Tax Architecture: Ireland-Domiciled (UCITS) Accumulating ETFs
For non-US investors utilizing global brokerages (such as Interactive Brokers), the legal domicile of a fund dictates decades of net compounding:
The Structural Mechanics of Irish-Domiciled UCITS ETFs:
- Estate Tax Immunity: Holding US-domiciled funds (e.g., VT, VOO) subjects non-resident aliens to US federal estate taxes of 26% to 40% on balances exceeding $60,000 upon death. Holding Irish-domiciled equivalents (e.g., VWRA, CSPX) listed on the London Stock Exchange eliminates US estate tax exposure entirely.
- Halved Dividend Leakage: Thanks to the US-Ireland bilateral tax treaty, internal withholding tax on US equity dividends is reduced from 30% to 15% within the fund structure.
- Frictionless Accumulation: Selecting the accumulating share class (where dividends are automatically reinvested into fund NAV) avoids taxable distribution events in territorial or capital-gains-free jurisdictions, maximizing multi-decade compounding.
III. Geographic Arbitrage: Four Resilient Havens for Sovereign Exit
In a FIRE framework, retreat does not mean primitive homesteading or bunker survivalism. It means leveraging the location independence unlocked by Human Capital Depreciation and Rational Career Exits to exploit wide asymmetries in living costs, physical security, healthcare quality, and tax burdens.
Target destinations must satisfy four physical prerequisites: high social cohesion, negligible violent crime, comprehensive tertiary healthcare within a 45-minute drive, and strong domestic agricultural security.
| Destination & Visa Pathway | 2026 Entry & Capital Requirements | Quality of Life & Institutional Profile | Practical Pitfalls & Compliance |
|---|---|---|---|
| Thailand: Destination Thailand Visa (DTV) / Retirement | DTV (Age 20+): Verifiable bank balance of 500,000 THB (~$14,500) held for 3 months; 10,000 THB processing fee. Retirement (Age 50+): 800,000 THB deposited in a Thai bank for 2 months prior. | 5-year multi-entry visa, 180 days per stay. Living expenses in Chiang Mai or Hua Hin run 40%–60% below Western capitals. Tier-one private medical care operates at roughly 20% of Western prices. | Strict background check and residence verification; brokerage screenshots are routinely rejected. Limit physical presence to under 180 days per calendar year to avoid triggering local tax residency. |
| Panama: Pensionado Visa | No minimum age. Requires a verifiable lifetime passive or retirement pension of at least $1,000/month (reducible to $750/month with a $100,000 real estate purchase). | Fast-track permanent residency. Fully dollarized economy operating a territorial tax system (zero tax on foreign-sourced income). Statutory discounts: 20% off healthcare, 25% off dining and utilities. | Physical presence requirement is minimal (visit once every two years to maintain status). Prioritize Boquete’s highland valleys or the Coronado coastline; avoid urban Panama City. |
| Costa Rica: Pensionado Residency | No minimum age. Must demonstrate guaranteed lifetime pension or passive annuity income of $1,000/month, covering the primary applicant and dependents. | Demilitarized, neutral republic with exceptional institutional stability. Features a recognized global “Blue Zone.” Access to the national CCSS healthcare system; fully insulated from geopolitical flashpoints. | All application documents must bear original Apostille certifications. Local employment is prohibited, though managing cross-border digital and capital assets is unrestricted. |
| Portugal: D7 Passive Income Visa | Primary applicant must demonstrate passive revenue of at least €920/month, backed by seasoned deposits (typically €11,040+ per adult) in a Portuguese bank. | Full access to the 27-nation Schengen Area. Regions like the Silver Coast and Madeira offer low crime rates, abundant sunshine, and high insulation from urban friction. | Requires a local tax number (NIF) and active bank account prior to filing. Maintain a 15% cash buffer above statutory minimums for FX moves. Structure residency days carefully to manage exposure to progressive tax brackets. |
IV. The Micro-Mechanics of FIRE: Safe Withdrawal Rates, Firewalls, and Independence
1. The Safe Withdrawal Rate: Calibrating to 3.25%–3.5%
The classic “4% rule” was derived from historical 30-year retirement horizons. For individuals exiting the corporate machinery between ages 35 and 45, a retirement phase can easily span 40 to 50 years. In an era of volatile real rates and sovereign balance-sheet strain, the Safe Withdrawal Rate (SWR) must be compressed to 3.25%–3.5%, requiring a capital base equal to 28.5 to 30 times annual expenditures:
Capital Requirements by Lifestyle Baseline
- LeanFIRE (Chiang Mai, Boquete, or coastal Southern Europe): $1,500/month ($18,000/year) requires a capital floor of $510,000 to $550,000.
- Comfortable FIRE (Secondary Spanish coast or nomadic dual-base): $2,500/month ($30,000/year) requires a capital floor of $850,000 to $900,000.
- Expat Barista FIRE: A portfolio of $200,000 to $300,000 combined with $1,000/month from low-friction remote consulting to cover base burn allows the core capital to compound uninterrupted in VWRA, reaching complete financial exit within 5 to 7 years.
2. Navigating the Three Pillars of Fiscal Predation
As explored in our critique of Social Security Tax Audits and Personal Defense Strategies, modern states systematically offload insolvency onto accumulated capital. Cross-border defensive planning requires addressing three structural traps:
- Net Wealth Taxes: Avoid establishing tax residency in jurisdictions like mainland Spain or Norway, where annual balance-sheet levies consume base capital irrespective of realized income.
- Unrealized Capital Gains Taxes: Stay clear of regimes attempting to tax unliquidated paper gains on mark-to-market valuations.
- Statutory Exit Taxes: Individuals carrying tax residency in high-tax European jurisdictions should orchestrate a clean exit before capital thresholds trigger punitive deemed-disposition exit levies.
3. Physical Redundancy and Information Fasting
True geographic arbitrage is not an ideological protest; it is the orderly reclamation of individual agency from systemic macro decline.
- Physical Redundancy: When leasing or buying in provincial enclaves, select properties with a 5–10 kWh distributed solar installation, storage batteries, and ample freshwater capacity. This guarantees ten or more days of full off-grid autonomy during municipal strikes or infrastructure failures.
- Deliberate Information Fasting: Cut the feeds of algorithmic outrage and polarized discourse. The unrest in metropolitan centers reflects the painful unwinding of an unsustainable entitlement consensus. Consuming that friction yields nothing but ambient anxiety while changing none of the underlying mechanics.
- Radical Realism: Redirect attention to what is tangible: physical training, serious reading, real food, and deep sleep. Use predictable passive cash flows to build an institutional moat, living quietly and deliberately while the old world argues with its own arithmetic.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。