The Fragility of the 4% Rule: Sequence of Returns Risk and Dynamic Capital Defense
The conventional FIRE axiom—accumulating 25 times annual expenses to maintain a static 4% withdrawal rate—exposes portfolios to a greater than 20% failure rate over 40-year horizons. Morningstar models now peg safe initial withdrawals at 3.3%. Mitigating total capital depletion requires dynamic spending guardrails, multi-year cash buffers, and geo-arbitrage.

Figure 1: Formulated in 1994, the 4% safe withdrawal rule assumes a rigid 30-year retirement window. Extended early-retirement horizons require a fundamental reconstruction of dynamic capital defense.
In the mainstream discourse surrounding early retirement, the assertion that accumulating 25 times one’s annual expenditure allows for a lifetime of passive income via the “4% Rule” is often accepted as an immutable truth. Yet this empirical framework, origin-dated to 1994, was engineered around a single key constraint: a 30-year retirement period commencing at age 65.
When individuals aged 35 to 45 extend their planning horizons to 40 years or half a century, the combination of static drawdowns and mechanical inflation adjustments breaks down under real-world market volatility. Morningstar’s long-term modeling indicates that to achieve a 90% portfolio survival rate over extended horizons, the safe initial withdrawal rate drops to 3.3%. For early retirees who encounter a bear market in their initial years, sequence-of-returns risk can permanently impair core capital, accelerating total portfolio depletion long before terminal life expectancy.
Thirty-Year Assumptions vs. Forty-Year Realities: The Structural Limits of Classic FIRE
The academic foundation of the 4% rule rests on William Bengen’s seminal 1994 paper and the subsequent 1998 Trinity Study. Their conclusions rely on rigid baseline parameters: a retirement age of 65, a portfolio split equally between the S&P 500 and intermediate U.S. Treasuries, and a fixed 30-year timeline. The historical stress test for this rule was the cohort retiring in 1966—on the eve of a brutal decade-plus period of stagflation and simultaneous stock-bond market declines. Even under those conditions, extracting an initial 4% and adjusting upward annually for inflation left a residual balance at the end of Year 30.
However, for early retirees, stretching the timeline from 30 years to 40 or 50 years fundamentally alters the underlying probability distribution. According to Morningstar’s Monte Carlo stress tests in The State of Retirement Income, the baseline safe withdrawal rate for a 30-year horizon fluctuates between 3.8% and 3.9%. Extend that timeline to 40 years, and an unadjusted initial withdrawal rate must be ratcheted down to 3.2%–3.3% to preserve a 90% historical survival probability.
If a 40-year-old early retiree dogmatically draws down an initial 4% and escalates that dollar amount alongside inflation regardless of asset performance, the risk of total portfolio exhaustion over a 40-year horizon rises above 20%. A detailed mathematical breakdown of multi-period variables for early retirement decumulation can be found in our analytical framework on FIRE Monte Carlo Simulations & Calculation Framework.
Sequence of Returns Risk: The Hidden Engine of Capital Degradation
Why can’t a portfolio’s long-term average annualized return save an early retiree from insolvency? The answer lies in the distinct mathematical mechanics governing the accumulation phase versus the decumulation phase.
During the accumulation phase, as long as an investor consistently buys and holds without liquidating capital, the chronological sequence of market volatility has zero bearing on the final portfolio value. A market that crashes for three consecutive years before surging for seven will yield the exact same 10-year compounded net asset value as a market that surges first and crashes later.
In the decumulation phase, this path-independence collapses. Financial planners define this vulnerability as Sequence of Returns Risk (SRR). In the critical window spanning 3 to 5 years before and after the transition into retirement, a deep market correction forces the investor to liquidate assets at depressed valuations to meet rigid living expenses. Liquidating shares during a market trough locks in real losses and permanently destroys core productive capital.
| Market Scenario | Static 4% Withdrawal Rule | Real-World Impact Under Sequence Risk |
|---|---|---|
| Deep Bear Market at Retirement Onset | Mechanically withdraws original dollar amount plus inflation by liquidating stocks/bonds | Liquidates core assets at steep discounts, forcing real drawdown rates higher and permanently truncating baseline equity |
| Mid-Cycle Bull Market Recovery | Relies on broad market mean-reversion to repair total balance sheet value | Core share volume was depleted early; portfolio cannot capture the full upside of the subsequent rally |
| 40-Year Horizon Terminal State | Assumes residual capital remains after 30 years | High probability of liquidity exhaustion between Years 15 and 25, leading to structural insolvency |
Consider the aftermath of the 2000 dot-com bust or the 2008 global financial crisis: an investor who retired at the onset of these drawdowns saw fixed dollar withdrawals consume an increasingly large percentage of their remaining assets. Even as markets subsequently entered long-term bull runs, the reduced share volume meant total portfolio capital could never recover its original compounding trajectory.
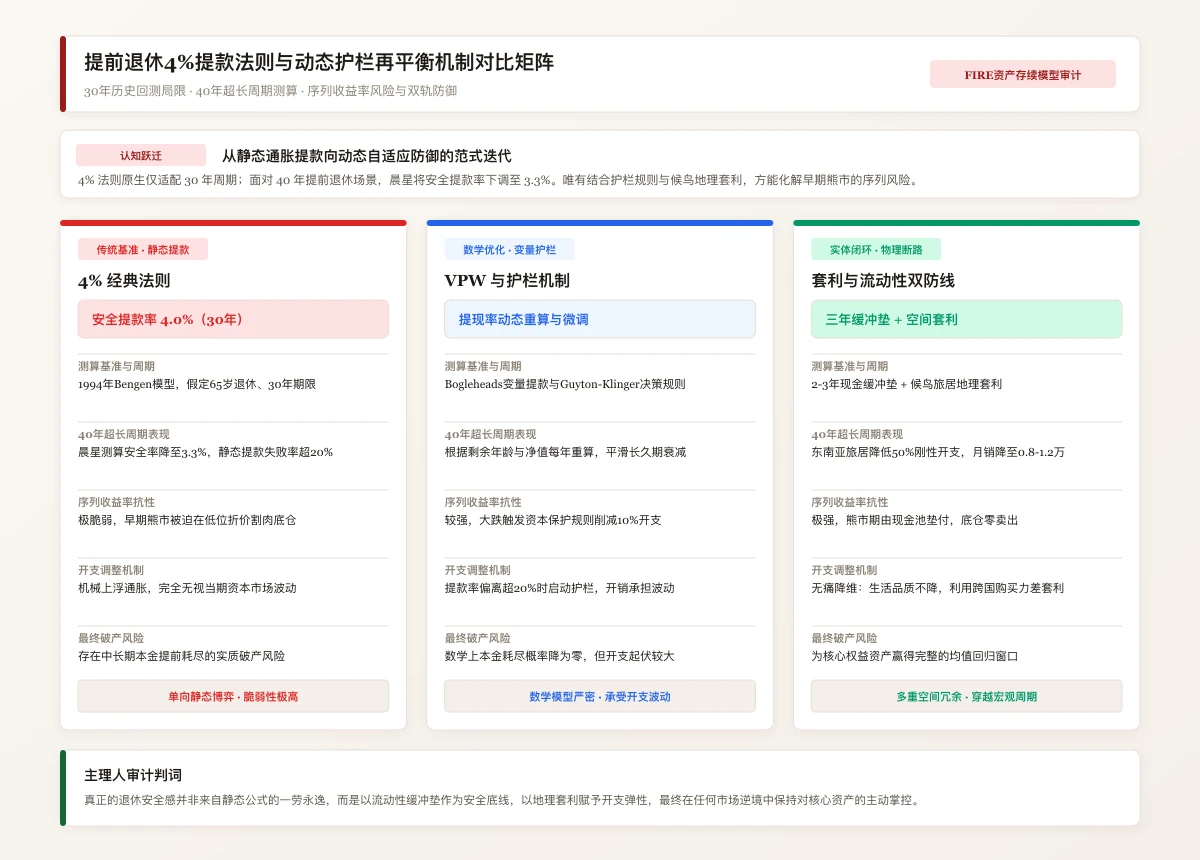
Figure 2: Cash flow mechanics and capital preservation profiles of static withdrawals versus dynamic variable guardrails across market cycles.
Variable Withdrawals and Guardrails: Exchanging Insolvency Risk for Expenditure Flexibility
Neutralizing sequence of returns risk requires abandoning the assumption of static spending adjusted purely for CPI. In practice, personal expenditures do not follow a rigid, upward-sloping line.
In financial literature, the Variable Percentage Withdrawal (VPW) methodology popularized by the Bogleheads community offers a mathematically grounded alternative. VPW calculates each year’s withdrawal rate based on the retiree’s current age, portfolio asset mix (e.g., 50/50 equities to fixed income), and the total real-time value of the portfolio at the beginning of the year. Because the dollar withdrawal is always a percentage of the remaining net asset base:
- When markets rally, expanded net worth automatically increases the spending budget;
- When markets suffer deep drawdowns, withdrawals contract proportionally, eliminating the mathematical probability of total portfolio ruin.
The trade-off of pure VPW is that portfolio volatility is transferred directly into daily living standards. To smooth out lifestyle turbulence, wealth management practice often adopts the dynamic guardrails popularized by Jonathan Guyton and William Klinger:
- Capital Preservation Rule: If a market decline causes the current effective withdrawal rate to rise more than 20% above the initial baseline rate, the current year’s withdrawal budget is trimmed by 10%, and the annual inflation adjustment is frozen. This modest cut halts the destruction of core equity during market troughs.
- Prosperity Rule: If a prolonged bull market drives the effective withdrawal rate more than 20% below the initial baseline, the retiree may increase discretionary spending.
The empirical dynamics of spending elasticity across different life stages are explored further in The Marginal Utility Inflection Point of Financial Freedom. Integrating spending flexibility grants portfolios critical room to absorb volatility during vulnerable market phases.
Geo-Arbitrage and Cash Buffers: Dual Circuit Breakers for Financial Survival
Relying entirely on micro-level budget cuts can induce chronic financial anxiety, often driving investors into panic selling during market downturns. Making a dynamic withdrawal model operational requires physical circuit breakers built into life architecture.
The first line of defense is an isolated liquidity buffer. Outside the core investment portfolio, maintain a cash reserve covering 2 to 3 years of non-negotiable fixed expenses in high-liquidity money market instruments or short-term Treasury bills. When equity markets experience a severe correction, suspend asset sales from stock and long-term bond portfolios entirely, drawing down living expenses from the cash buffer instead. This provides core equities a full multi-year window to recover. Structural guidelines for building tiered reserves are detailed in FIRE Kill-Line Defense and Liquidity Reserves.
The second line of defense is geographical arbitrage. Cost of living is not a fixed constant; it is a function of spatial coordinates. In tier-one global cities, baseline family expenditure often runs $3,000 to $4,500 per month. Transitioning to low-cost regional hubs—such as Chiang Mai, Penang, or Kuala Lumpur—can reduce average monthly outlays to $1,200–$1,800 without sacrificing housing quality, healthcare access, or lifestyle amenities. This represents a structural spending reduction of over 50%.
During periods of elevated market valuations and macro uncertainty, shifting spending across geographies leverages purchasing power differentials to construct an unwritten insurance policy around domestic investment portfolios. Retirees can enjoy international mobility during market stability, then lower their burn rate to ride out market dislocations. Long-term early retirement sustainability rests not on static withdrawal formulas, but on dynamic adaptability.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。