The Geo-Arbitrage Trap: Auditing Chiang Mai, Lisbon, and the Architecture of FIRE Cash-Flow Resilience
While benchmark indexes pitch Chiang Mai and Lisbon at $1,450 CAD and $2,950 CAD per month, true international living extends far beyond nominal price conversions. Currency swings, seasonal pollution flights, and 180-day tax residency traps can quickly erode purchasing power without a multi-tiered liquidity strategy.

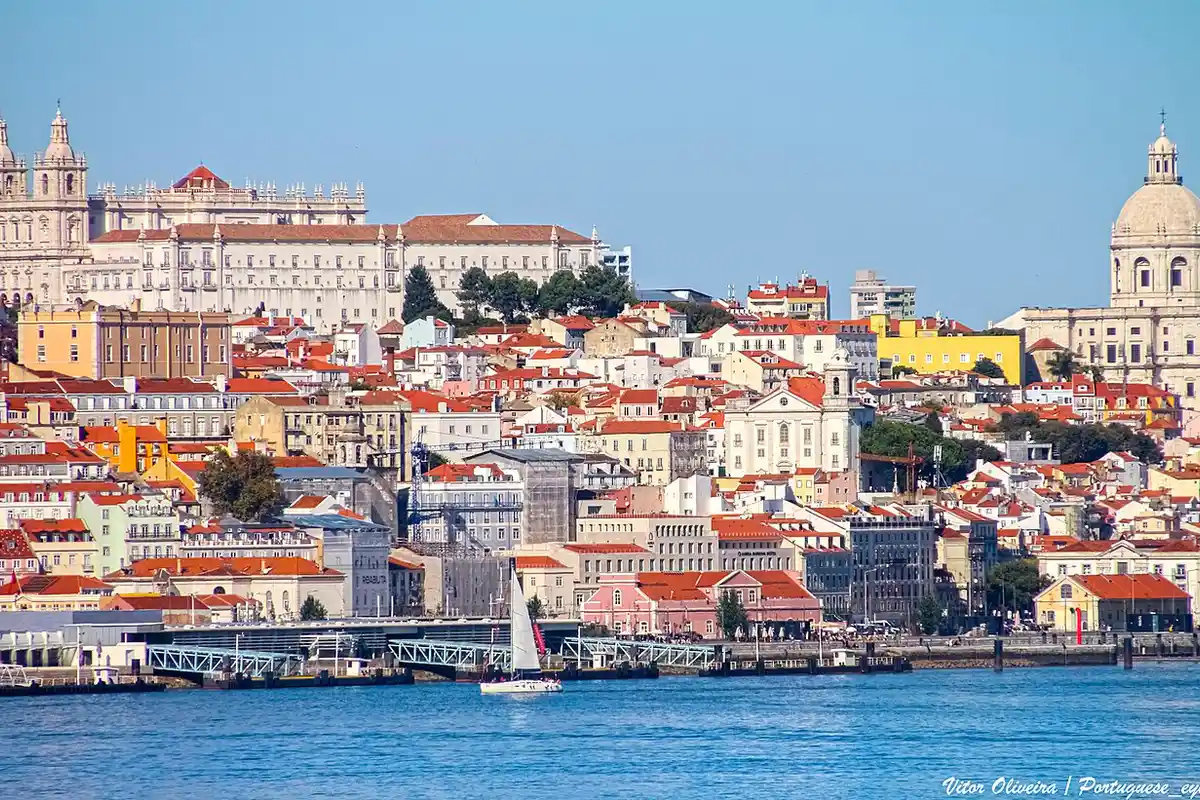
Figure 1: Tram and skyline in Lisbon’s historic quarter. As a premier temperate European winter destination for digital nomads, its baseline cost of living and legal entry thresholds have undergone a profound structural shift.
In Money.ca’s index of global winter escapes, Chiang Mai, Thailand, and Lisbon, Portugal, were assigned baseline single-person monthly budgets of $1,450 CAD and $2,950 CAD, respectively. This more than two-fold divergence has reignited debate within the digital nomad and FIRE (Financial Independence, Retire Early) communities over the actual efficiency of geographic arbitrage.
Yet, establishing an international footprint is rarely a matter of simple nominal prices and spot currency conversions. Unidirectional exchange-rate swings, imported rental inflation, seasonal evacuation flights, and territorial tax residency rules anchored to 180- or 183-day thresholds all act as non-linear drains on real purchasing power. Relying on static low-cost assumptions without dynamic cash-flow protections is often the first step toward long-term financial imbalance.
The Illusion of Nominal Cost: Deconstructing Chiang Mai ($1,450 CAD) vs. Lisbon ($2,950 CAD)
Under Money.ca’s methodology, the monthly budgets for these two anchor destinations reflect fundamentally distinct socioeconomic models:
- Chiang Mai, Thailand (~$1,450 CAD/month): This estimate accounts for a fully furnished one-bedroom apartment in the urban core, frequent dining out, co-working space access, and local transit. Benefiting from exceptionally low domestic service and hospitality costs, a nomad working from specialty cafes and dining at local markets can keep daily overhead to a modest fraction of Western equivalents.
- Lisbon, Portugal (~$2,950 CAD/month): This baseline merges roughly €800 (
$1,220 CAD) in food and lifestyle expenses with €1,093 ($1,670 CAD) for a one-bedroom apartment outside the historic center. Lisbon delivers a mild Southern European winter climate, high-standard EU healthcare access, and rich cultural infrastructure—yet its entry-level cost profile sits at double that of Southeast Asia.
| Metric / Dimension | Chiang Mai, Thailand | Lisbon, Portugal | Underlying Financial Mechanics |
|---|---|---|---|
| Nominal Monthly Expense | ~$1,450 CAD | ~$2,950 CAD | Lisbon’s entry baseline runs ~2.03x higher than Chiang Mai. |
| 1-Bed Rent Baseline | ~$400–$600 CAD (City Center) | ~€1,093 / ~$1,670 CAD (Non-Core) | European metropolitan housing suffers rigid supply bottlenecks. |
| Dining & Services | Ultra-low (~$2–$3 CAD street meals) | Mid-tier European (~€800/mo baseline) | Generational wage and service labor cost differentials. |
| Legal Visa Threshold | Tourist / DTV (Destination Thailand Visa) | D7 Passive Income Visa (€920/mo minimum) | European long-term residency mandates verifiable statutory passive yield. |
| Climate & Seasonality | Cool Nov–Jan; severe haze Feb–Apr | Mild and humid year-round; rainy winters | Burning season forces cross-border relocation costs in Chiang Mai. |
Too many practitioners of geographic arbitrage stop at static comparison charts like this one. Plugging local nominal prices directly into home-currency withdrawal formulas, they conclude that moving to Southeast Asia will slice a decade off their required working years. But real-world cross-border cash flows are subject to three persistent operational frictions.
The Three Hidden Frictions of Geographic Arbitrage
Divorced from the safety of a single-currency environment, international long-term residents face non-linear expenditure surges across three distinct vectors:
1. Asymmetric Foreign Exchange Fluctuations
Most FIRE practitioners hold their primary yield-generating assets in US Dollars, Canadian Dollars, or Chinese Yuan, while local expenses settle inflexibly in Thai Baht (THB) or Euros (EUR). Emerging market currencies and major foreign exchange pairs regularly experience cyclical fluctuations of 15% to 25%.
When a home currency weakens while the local host currency strengthens, nominal living costs in home-currency terms surge overnight, swallowing the expected arbitrage margin. Liquidating depreciated home assets month by month to meet rising local currency bills inflicts permanent portfolio damage—a dynamic detailed in our analysis of [Cost of Living Exodus in Australia and Global Geo-Arbitrage](/posts/australia-cost-of-living-exodus-geoarbitrage/).
2. Chiang Mai’s Burning Season and Double-Rent Costs
Chiang Mai does not enjoy year-round ideal weather. From February through April—peaking in March—the region’s topography combines with agricultural burning and regional forest fires to push AQI and PM2.5 readings into hazardous territory.
To mitigate health risks, long-term digital nomads must plan an annual retreat to southern islands like Phuket or Samui, or to neighboring countries. This seasonal migration triggers extra airfare and short-term hospitality costs. If the nomad retains a primary annual lease in Chiang Mai, they incur two to three months of overlapping double rent, raising the annualized monthly average cost significantly above nominal projections.
3. Imported Rental Inflation and Liquidity Locks in Lisbon
Unlike Chiang Mai’s elastic housing supply, Lisbon has absorbed massive inflows of Western remote workers and high-net-worth arrivals over the past several years. Downtown long-term and short-term rental markets have expanded rapidly under foreign capital demand, exposing incoming tenants to a two-tier price structure far above local median income levels.
Securing a quality long-term lease outside the core often requires securing the deal months in advance or pre-paying six to twelve months of rent upfront, locking up essential liquid capital.
Legal and Tax Vulnerabilities: Thailand’s Order Por. 161/2566 and Portugal’s 183-Day Threshold
The most dangerous blind spot in geographic arbitrage is conflating tourist status with tax residence. As global tax transparency frameworks (CRS) mature and territorial authorities tighten their tax codes, compliance costs for long-term international residents scale exponentially.
Thailand’s Remittance Tax Enforcement (Orders Por. 161/2566 & 162/2566)
Historically, long-term foreign residents in Thailand relied on an informal interpretation of tax rules that exempted offshore income from local taxation if it was remitted in a calendar year after it was earned. Instructions Por. 161/2566 and Por. 162/2566 from the Thai Revenue Department dismantled this workaround:
- 180-Day Tax Residency: Under Section 41, Paragraph 3 of the Thai Revenue Code, any individual staying in Thailand for an aggregate of 180 days or more in a single calendar year (January 1 to December 31) is classified as a Thai tax resident.
- Taxation on Remitted Foreign Income: Effective January 1, 2024, assessable income earned offshore by a tax resident—and subsequently remitted into Thailand to cover living costs, rent, or assets—must be declared for personal income tax, subject to progressive rates ranging from 0% to 35%. The mechanics of this shift are analyzed further in
[Thailand LTR Visa & Phuket Nomad Tax Compliance](/posts/thailand-ltr-visa-tax-phuket-nomad-arbitrage/).
Nomads relying on international wire transfers or local ATM withdrawals to fund daily expenses risk exposing their capital gains and dividend income to back-taxes and mandatory declarations once they cross the 180-day threshold.
Portugal’s Elevated D7 Threshold and the Sunset of NHR
In Portugal, legal entry and tax obligations have undergone a similar structural shift:
- Passive Income Threshold: Applicants for the D7 passive income visa must demonstrate certified passive earnings equal to at least 100% of the national minimum wage (€920/month, or ~$1,441 CAD, in 2024), a figure adjusted upward annually.
- Sunset of the NHR Regime: Portugal officially ended its traditional Non-Habitual Resident (NHR) tax scheme—which offered a 10-year flat 10% tax rate or exemptions on foreign pensions and specific passive incomes—replacing it with a narrower incentive focused primarily on corporate R&D and academic talent. Once a resident spends 183 days in Portugal and becomes a tax resident, global investment yields, interest, and dividends fall under standard progressive tax brackets up to 48%, plus solidarity surcharges. For a deeper evaluation of residency structuring, see
[Portugal Golden Visa & CRS Cross-Border Tax Audits](/posts/portugal-golden-visa-crs-cross-border-tax-audit-2026/).
Failing to track tax residency status can wipe out years of nominal price savings in a single annual tax assessment.
The Three-Tier Cash-Flow Defense Pyramid: Neutralizing FX Shocks and Dynamic Withdrawal Limits
To withstand currency shifts, nominal budget discrepancies, and tax enforcement, experienced international practitioners avoid rigid 4% static withdrawal strategies. Instead, they structure their capital across a multi-tiered reserve model.
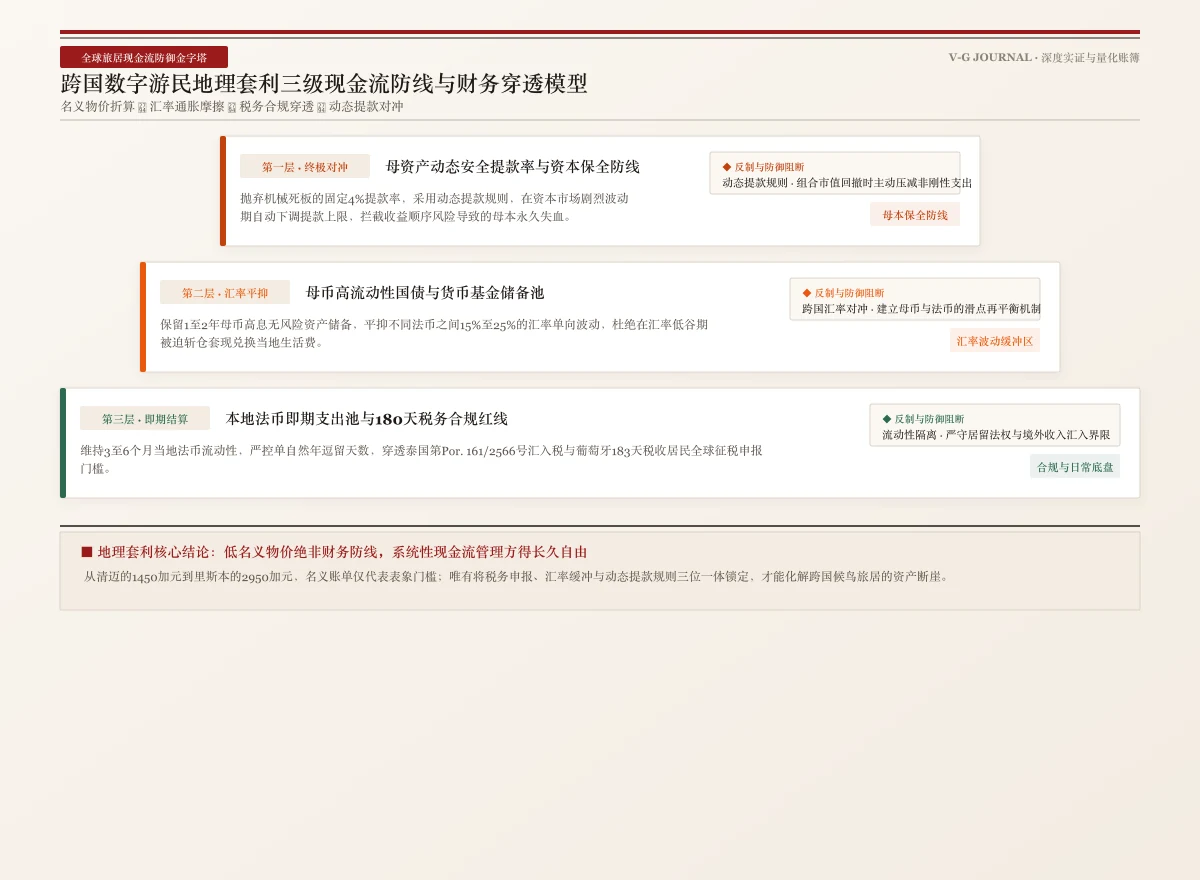
Figure 2: The Three-Tier Cash-Flow Defense Pyramid for cross-border nomads, built to absorb currency shocks, buffer against sequence-of-returns risk, and enforce tax-residency compliance.
Tier 1 · Capital Preservation: Dynamic Safe Withdrawal Rates (SWR)
Applying a traditional US-centric 4% fixed rule in a multi-currency context introduces severe sequence-of-returns risk. If global equity markets suffer a drawdown while the local currency of your host country appreciates, maintaining a fixed nominal withdrawal forces you to sell equities at a bottom, causing permanent portfolio impairment.
Modern cross-border portfolios incorporate dynamic withdrawal guardrails (such as Guyton-Klinger capital preservation rules):
- Capital Preservation Rule: If market declines push the current withdrawal rate above a pre-set threshold, non-essential travel and lifestyle spending are trimmed immediately, deferring high-cost European trips to protect underlying equity principal;
- Dynamic Rebalancing Integration: For a quantitative breakdown of guardrail mechanics, see our framework on
[Dynamic Safe Withdrawal Rates and Asset Rebalancing Models](/posts/fire-safe-withdrawal-rate-failure-dynamic-rebalancing/).
Tier 2 · FX Smoothing: Home-Currency Treasury and Liquidity Buffers
To remove the friction of 15% to 25% foreign exchange swings, portfolios should maintain a 1- to 2-year buffer of high-grade, home-currency risk-free assets (such as short-term T-bills or money market funds).
- When host currencies sit at historical highs and exchange rates are unfavorable, you avoid liquidating core equity holdings, drawing instead on yield from the cash reserve.
- When exchange rates return to historical averages or reverse cyclically, you replenish local spending accounts in larger tranches.
Tier 3 · Spot Settlement: Local Currency Operations and the 180-Day Boundary
At the operational layer, maintain 3 to 6 months of local spending liquidity held in multi-currency digital accounts (e.g., Wise or Revolut) to cover day-to-day living costs.
- Strict Day-Count Management: Unless establishing a formal, permanent tax home is part of your long-term plan, keep annual stays below 180 days in Thailand or 183 days in Portugal. This preserves non-resident status and protects global assets from local tax exposure.
- Migratory Seasonal Rotation: A practical routine might involve staying in Chiang Mai from November to January for peak climate and low costs, moving away from northern Thailand during the February–April burning season, and spending May to September in Southern Europe—balancing lifestyle quality with tax compliance.
From Chasing Low Cost to Mastering Capital Sovereignty
From Chiang Mai’s $1,450 CAD monthly entry point to Lisbon’s $2,950 CAD Atlantic profile, cost-of-living rankings provide helpful starting data points. Yet geographic arbitrage is not simply a search for the lowest nominal price tag on a map. Done right, it is a framework for structuring life across borders to maximize personal freedom, legal stability, and capital preservation per dollar spent.
True financial resilience does not come from relentless frugality, but from total control over your underlying cash flow: maintaining cash reserves when currencies swing, preserving the freedom to move when seasons change, and keeping a clear compliance buffer against shifting tax codes. By integrating spot fiat management, home-currency yield buffers, and dynamic withdrawal rules, cross-border living evolves from a fragile low-cost illusion into a durable strategy for long-term independence.
Related Research & Topics
The Maritime Insolvency of Lifetime Nomadism: Fuel Shocks, Contractual Illusions, and the Subordination of Unsecured Claims
The Illusion of Physical Safety: Goldman’s Revised Gold Timeline and the Sovereign Friction Facing Nomad Portfolios
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。