US$2.8 Trillion Wiped Out: Sequence of Returns Risk and the FIRE Withdrawal Defense Line
On November 5, 2026, the US stock market shed $2.8 trillion in a single session, plunging the Nasdaq into correction territory. For the FIRE community dependent on rigid withdrawals, this systemic shock highlights the brutal mechanics of Sequence of Returns Risk—where early-cycle drawdowns and leverage can permanently destroy capital.

Figure 1: On November 5, 2026, US equities suffered a concentrated sell-off. Major indices took a severe hit, with technology and semiconductor sectors leading the descent.
On November 5, 2026, the US stock market endured a punishing liquidation wave. Approximately US$2.8 trillion in market capitalization evaporated in a single trading session. The Nasdaq Composite plummeted 5.52%, officially entering technical correction territory, while the Philadelphia Semiconductor Index collapsed by 12.25%. For cross-border FIRE (Financial Independence, Retire Early) practitioners who are fully invested in tech-heavy broad-market indices and rely on the rigid 4% rule, this drawdown serves as a blinding wake-up call. It shatters the capital illusions of the high-valuation AI industrial chain and drags a long-ignored mathematical threat into the spotlight: the Sequence of Returns Risk.
When a deep market crash strikes at the very inception of a retirement withdrawal phase, plunging asset values combined with inflexible living expenses trigger a destructive feedback loop, inflicting permanent, irreversible damage to the principal.
I. The Real Catalyst and Valuation Reset
Trading logs and statistical records confirm that the November 5 sell-off marked a milestone in recent market history. The single-day evaporation of roughly US$2.8 trillion eclipsed peak daily losses seen since the COVID-19 pandemic. The epicenter was heavily concentrated in technology stocks with rich preceding gains, which shed US$2.5 trillion alone. The “Magnificent Seven”—long regarded as the ultimate ballast of US equities—saw approximately US$1 trillion wiped out in a single day.
The structural stampede across major core indices highlights the breadth of the shock:
| Market Index / Sector | Performance on November 5, 2026 | Technical & Historical Standing | Primary Risk Bearer & Impact Profile |
|---|---|---|---|
| Nasdaq Composite | Down 5.52% | Retreated over 10% from historical highs; entered formal technical correction. | Tech and growth sector leaders; core holdings of growth-oriented passive dollar-cost averters. |
| Philadelphia Semiconductor Index (SOX) | Plunged 12.25% | Largest single-day drop since March 2020. | Chip manufacturing and AI compute supply chain; high-Beta concentrated holdings severely hit. |
| S&P 500 Index | Down 4.36% | Broad-based large-cap pullback; major bullish defense lines breached. | Core underlying assets for classic FIRE retirement portfolios. |
| Dow Jones Industrial Average | Down 3.44% | Reversed from intraday gains; dropped over 1,800 points on the day. | Traditional industrials and high-dividend assets swept up in liquidity contagion. |
The immediate trigger for the crash was a dual resonance of political shifts and fundamental re-pricing. Following the US midterm elections, the Democratic Party regained control of both houses of Congress. Lawmakers immediately moved to impose stricter environmental and energy-consumption reviews on power-hungry, large-scale AI data centers. This shattered the market’s prior consensus regarding the infinite, unconstrained expansion of compute infrastructure.
Simultaneously, Wall Street began scrutinizing the staggering capital expenditures (Capex) poured into AI by hyperscale cloud providers. Guidance figures from tech bellwethers like Qualcomm failed to meet overly inflated expectations, forcing capital to re-evaluate the commercial payback timeline of massive infrastructure outlays. Within a heavily crowded bullish positioning structure, shifting sentiment rapidly mutated into a hedge-fund de-leveraging stampede, draining liquidity across sectors.
II. Sequence of Returns Risk: The Mathematical Inversion of the Withdrawal Phase
For investors still in the “Accumulation Phase” of their careers, an index drawdown of 4% to 5.52%—or even deeper—is usually viewed as an opportunity to buy discounted shares via dollar-cost averaging. However, the moment one crosses the FIRE threshold into the “Distribution Phase,” the chronological sequence of returns completely rewrites portfolio survival probabilities.
This is the financial reality known as Sequence of Returns Risk. Its core mechanism is straightforward: Negative returns in the first 5 to 10 years of retirement are dozens of times more lethal than volatility experienced later in the cycle.
The classic 4% rule stems from the Trinity Study, which backtested historical stock and bond data based on a traditional financial model: retirement at age 60 with a 30-year time horizon. If a market crash occurs in year one of retirement, the investor is forced to sell a vastly higher volume of shares than originally planned simply to fund fiat-denominated living expenses.
Assume an investor’s net worth drops by 30% due to a market downturn. To maintain the original fiat payout calculated from their initial baseline capital, the actual percentage withdrawn from the now-depleted portfolio spikes to 5.7% or higher. These discounted equity assets, liquidated at market bottoms, are permanently removed from the portfolio, resulting in a Permanent Destruction of Capital. Even if the market stages a robust recovery years later, the core share count has been severely depleted. The compounding engine of the portfolio is permanently crippled, leaving it unable to regain its prior watermarks.
This forced passive erosion—driven by restricted liquidity access or fire-sale pricing—mirrors patterns observed in physical asset domains. As analyzed in the exploration of the liquidity boundaries and financial hedging of low-total-value older apartments in Changsha for rental retirement, legacy real estate assets face protracted liquidation cycles and steep transaction frictions during market corrections. Desperate sellers often face punishing discounts. While secondary financial markets execute in milliseconds, panic-driven withdrawals during severe drawdowns without liquidity isolation inflict physical damage to the portfolio’s foundation that is structurally identical to real estate fire-sale haircuts.
III. The Fragility of Leveraged Amplification and Liquidity Runs
During the bull market euphoria of recent years, a cohort of younger individuals pursuing early retirement sought to compress their accumulation timelines by introducing aggressive leverage into their portfolios. Tactics ranged from heavy allocation to 1.5x to 3x leveraged ETFs to drawing down low-interest fiat via Lombard loans or margin accounts against stock collateral, betting that long-term capital gains would effortlessly outpace borrowing costs.
Yet, the double-edged sword of leverage reveals itself ruthlessly during liquidity contractions. When the Nasdaq plunges 5.52% in a single day and the semiconductor sector drops 12.25%, leveraged holders face single-day net-worth collapses ranging from 8% to over 36%.
As equity values breach maintenance thresholds, brokerage systems automatically issue margin calls. Absent external liquidity injections to top up accounts, pledged assets undergo forced liquidation at the intraday market bottom. This cascading feedback loop is a recurring motif across high-volatility financial markets. As demonstrated in Binance compliance flash points and liquidity shocks: Asset preservation and cash-out risk control under extreme conditions, leveraged structures lacking physical insulation inevitably trigger cascading liquidations during extreme liquidity drains, causing seemingly robust balance sheets to self-destruct within hours.
IV. A Multi-Dimensional Defense Matrix: Cash Buffers and Dynamic Guardrails
Neutralizing the fatal blow of Sequence of Returns Risk on an early retirement plan requires abandoning the one-dimensional model of “100% equities plus a mechanical 4% withdrawal rate.” It demands an asset allocation architecture equipped with liquidity insulation.
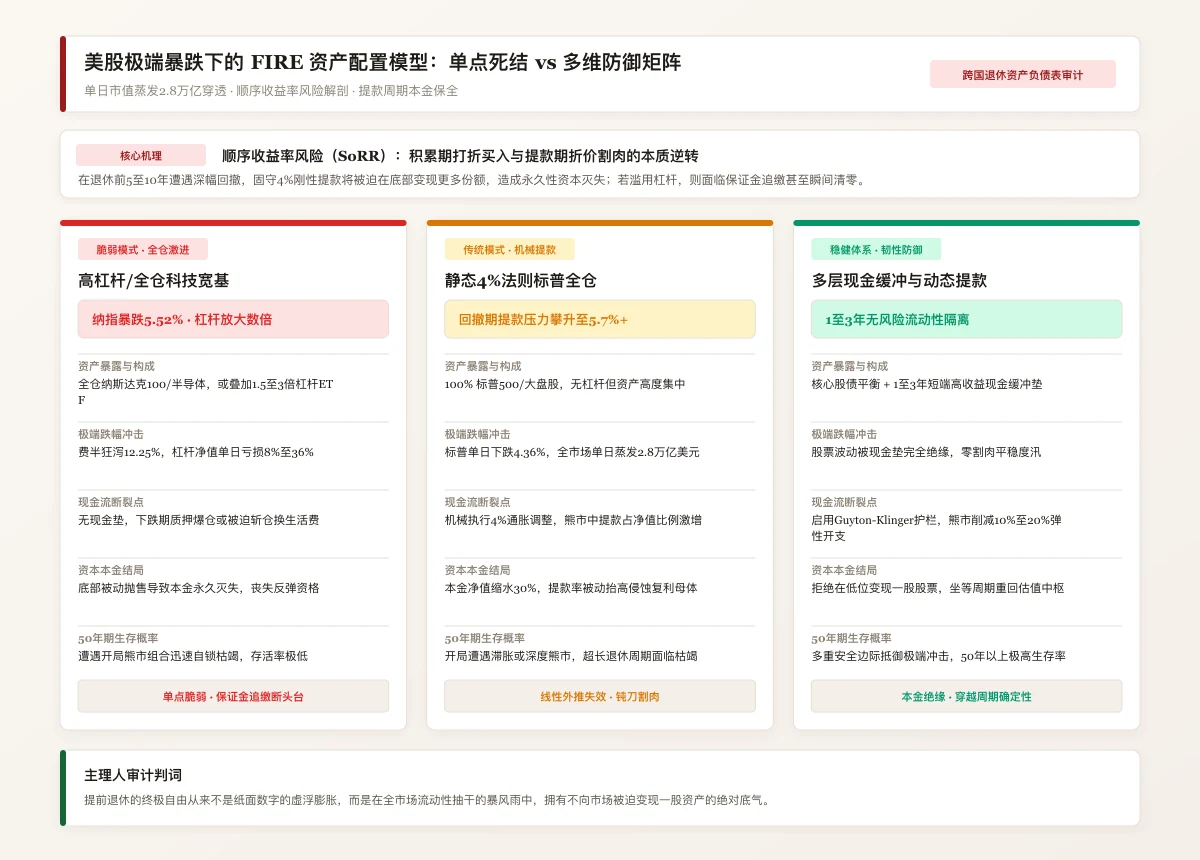
Figure 2: Comparative FIRE asset allocation models under extreme market drawdowns: Single-point fragile model, traditional mechanical withdrawal, and multi-layered liquidity defense.
Building a retirement withdrawal framework capable of surviving multi-decade market cycles requires fortifying three core dimensions:
1. Establish a 1-to-3-Year Risk-Free Short-Term Liquidity Buffer
The primary defense against being forced to sell at the bottom is achieving physical insulation between living cash flow and equity market valuations. Investors should segregate 1 to 3 years’ worth of rigid living expenses into risk-free, short-duration instruments such as short-term treasury bills, high-grade certificates of deposit, or money market funds.
When the US market experiences an extreme shock like a US$2.8 trillion single-day loss, current living expenses are funded smoothly by the cash buffer. Not a single share of the underlying equity portfolio needs to be sold. This buys ample time for equity assets to weather valuation corrections and await cyclical recovery.
2. Deploy Guyton-Klinger Dynamic Withdrawal Guardrails
The static 4% rule assumes investors mechanically adjust withdrawals upward for inflation every single year—a perilous assumption across a 40- to 50-year retirement horizon. A more resilient strategy incorporates dynamic guardrails: in years following significant portfolio drawdowns, non-essential, discretionary spending is voluntarily pared back by 10% to 20%, delaying luxury consumption or costly travel. Conversely, in years marked by outsized market gains, the upper withdrawal limit can be adjusted upward. This flexibility in expenditure dampens permanent capital destruction rates during adverse market openings.
3. Unlock the Cost-of-Living Elasticity of Cross-Border Geographic Arbitrage
For FIRE practitioners adopting cross-border mobility and digital nomadism, freedom of geographic relocation serves as a natural hedge against financial volatility. As detailed in Digital Nomad vs. FIRE: Calculating the True Liquidity Ledger Between Geographic Arbitrage and Early Retirement, cross-border mobility is not merely a lifestyle choice—it is a functional financial defense mechanism.
When dollar-denominated equity assets face cyclical valuation resets, retirees residing in lower-cost-of-living regions can effortlessly compress their total fiat expenditure, navigating turbulent windows with minimal cash burn. This capacity to dynamically recalibrate living cost structures provides a far sturdier margin of safety than rigid arithmetic assumptions about asset figures.
The freedom pursued through early retirement was never built on paper-asset inflation during bull market tailwinds. True freedom is the peace of mind that comes from knowing, when market-wide liquidity shocks strike, that you are never forced to liquidate assets at the bottom.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。