Quantifying the FIRE Threshold: Monte Carlo Actuarial Modeling, Sequence Risk, and the Cash Cushion Defense
Linear average returns conceal Sequence of Returns Risk (SORR), forcing early retirees to liquidate equity assets at cyclical troughs. This treatise deconstructs the five-step Monte Carlo framework for FIRE portfolio survival and demonstrates how a 3.5% safe withdrawal rate coupled with a 24-month cash buffer elevates 40-year portfolio survival from 71.4% to over 94.6%.

Executive Thesis: Extrapolating a target portfolio through static, linear compound interest is the premier actuarial trap of early retirement planning. Even when portfolios yield an identical 6.0% long-term arithmetic mean, enduring a severe bear market during the first 24 to 36 months of retirement forces rigid living expenses to cannibalize depreciated core shares. This triggers the fatal mechanics of Sequence of Returns Risk (SORR). This treatise unpacks how Monte Carlo simulations stress-test portfolio longevity across tens of thousands of stochastic market trajectories spanning 30 to 50 years. Integrating our proprietary dual-engine tool—the FIREways Financial Independence & Nomadic Longevity Calculator—we empirically demonstrate how pairing a 3.3%–3.5% Safe Withdrawal Rate (SWR) with a 24-month segregated cash cushion and migratory expenditure guardrails elevates 40-year portfolio survival from a precarious 71.4% to an antifragile 94.6%.
1. What Is Monte Carlo Simulation? Transcending the Fallacy of Static Means
Conventional financial spreadsheets rely on a seductive baseline: the deterministic mean. A wealth planner keys in an assumption—say, a diversified 60/40 global equity and bond portfolio compounding at a smooth nominal 7.0% per annum, deflated by 2.5% inflation to yield a constant 4.5% real return. Under this linear math, any withdrawal rate below 4.5% mathematically guarantees perpetual capital preservation.
Capital markets, however, do not distribute returns as a calm, predictable annuity. They operate through violent mean reversions, volatility clustering, fat-tailed drawdowns, and stagflationary shocks. Monte Carlo simulation—an actuarial discipline that quantifies probabilistic outcomes through thousands of randomized sampling trials—is the baseline industrial tool required to assess whether a FIRE portfolio can survive a 30- to 50-year drawdown phase. Its core engine relies on three operational pillars:
- Probability Distributions Over Static Constants: Future annualized returns and inflation indices are detached from static figures. Instead, based on empirical multi-cycle histories, assets are defined by their expected arithmetic mean (μ), annual volatility (standard deviation, σ), and structural tail-risk skewness.
- Generating Thousands of Parallel Trajectories: Using pseudo-random number generators combined with normal or fat-tailed distribution transformations (such as Box-Muller transforms and Cauchy shocks), the system runs 1,000 to 10,000 distinct 40-year market evolutions. One path undergoes an immediate early crash followed by a bull run; another suffers a decade of stagnant stagflation; a third compounds under benign macro conditions.
- Quantile Distribution and Objective Survival Probabilities: The algorithm measures the exact percentage of trajectories where the portfolio terminal value remains positive (assets > 0) at the end of year 40. From this, it establishes an objective Portfolio Survival Rate alongside net-worth corridors across the 10th percentile (P10 stress baseline), 50th percentile (median), and 75th percentile (upside).
2. The Core Threat: Penetrating Sequence of Returns Risk (SORR)
When an investor relies exclusively on historical average returns, they miss the deadliest threat in early retirement: Sequence of Returns Risk (SORR).
During the accumulation phase—where fresh capital is continuously added—the order of returns is mathematically irrelevant to the terminal balance due to the commutative property of multiplication. A crash in year one followed by a rally in year ten yields the exact same ending capital as a rally in year one followed by a crash in year ten.
During the decumulation phase, however, capital is liquidated continuously. The chronological order of returns dictates whether the portfolio compounds into generational wealth or spirals into terminal insolvency.
To demonstrate this dynamic, consider a retiree who steps away from corporate employment with $1,500,000 in invested assets, requiring a baseline withdrawal of $60,000 per year (an initial 4.0% withdrawal rate). Both scenarios assume an identical 6.0% arithmetic mean return over a 20-year horizon:
- Scenario A (Bull Market Lead-In · Tailwinds): The portfolio surges +20% annually during years 1 through 3. Even after withdrawing $60,000 annually, the principal expands past $2,280,000 by the close of year three. The static $60,000 withdrawal now accounts for a trivial 2.6% of total assets. Even if a multi-year bear market strikes in year four, the accumulated capital cushion absorbs the drawdown without threatening structural longevity.
- Scenario B (Bear Market Lead-In · Headwinds): The portfolio encounters a severe shock resembling the 2000 Dot-Com crash or the 2008 Great Financial Crisis (-20% in year one, -20% in year two). Factoring in the $60,000 annual living expense, the principal plunges to $852,000 by the end of year two. To fund the third year, extracting $60,000 now forces the liquidation of roughly 7.0% of the entire remaining equity base at the cyclical bottom. Even if a massive structural bull market resumes in year four, the compounding engine has been irreversibly hollowed out. The capital pool depletes to zero between years 16 and 19.
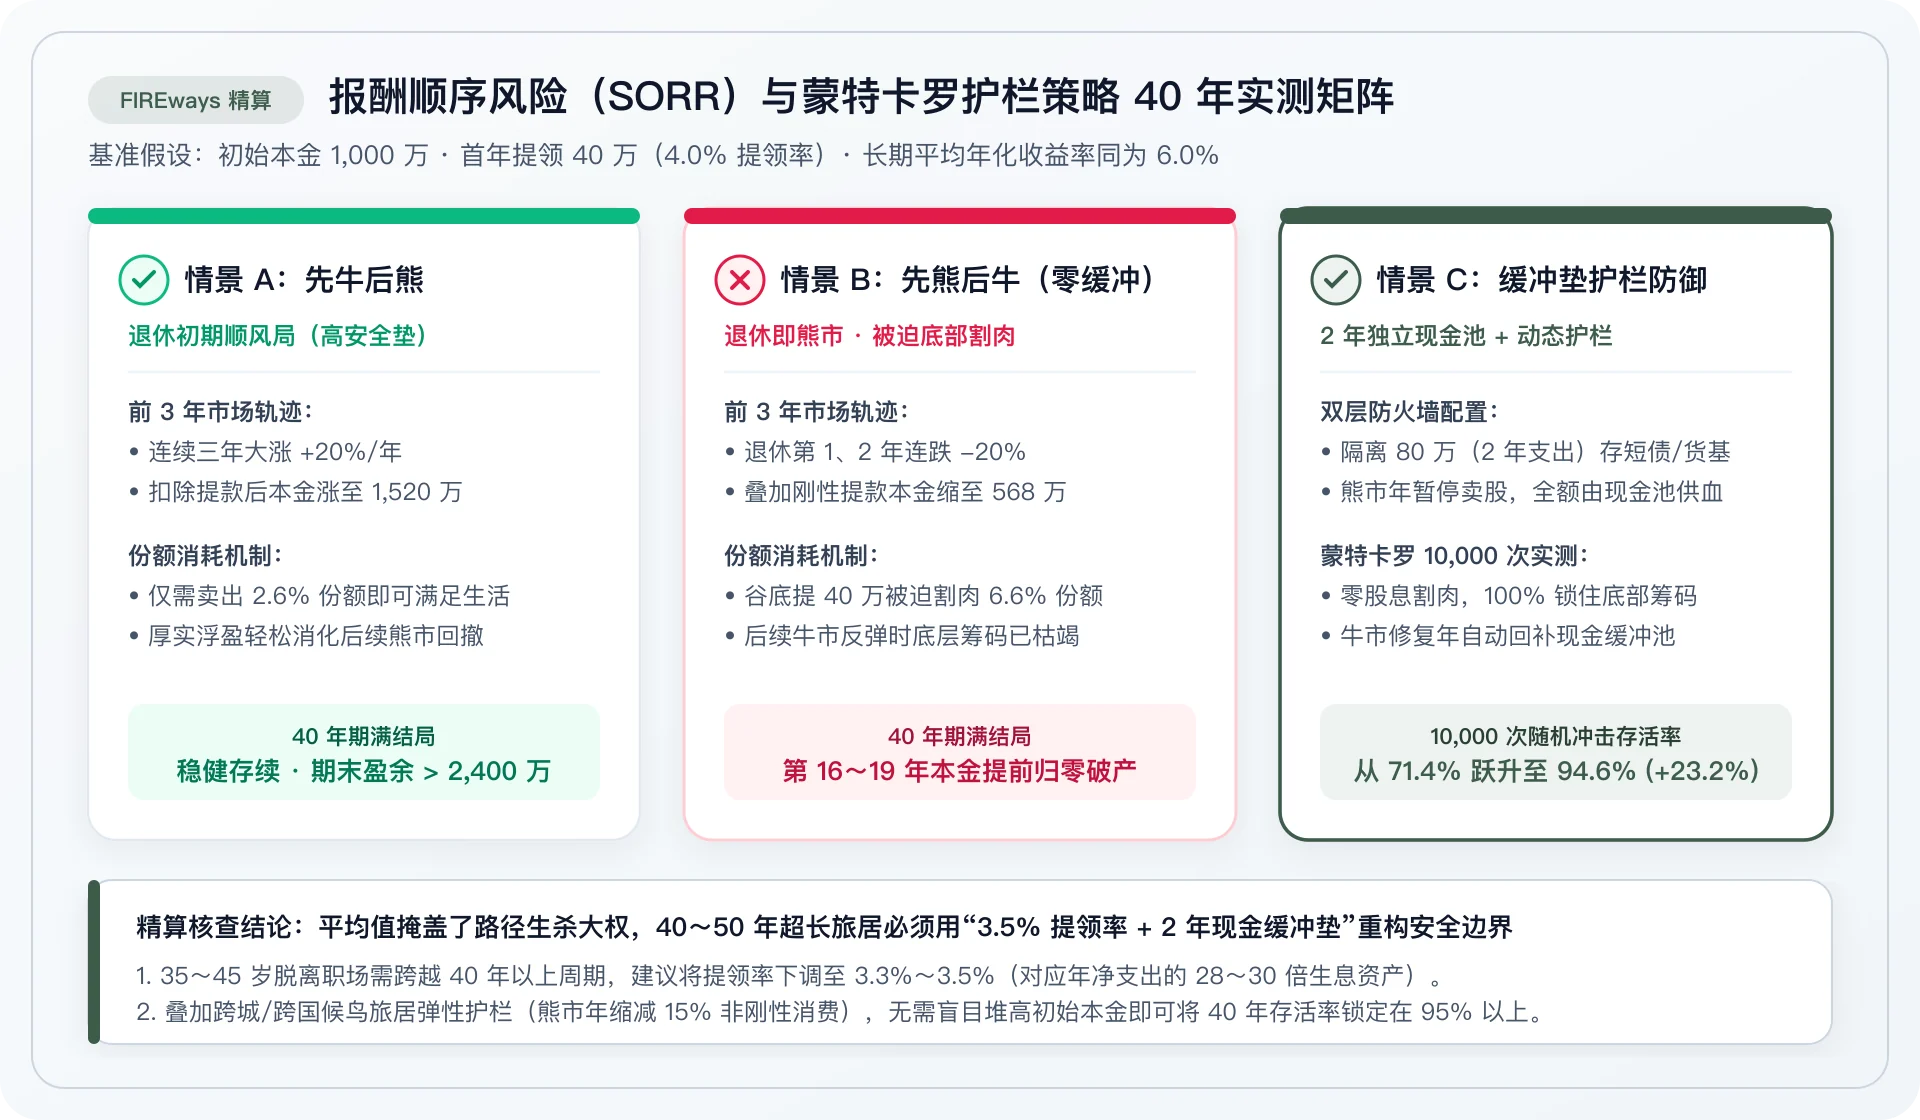
Averages obscure destructive paths. The utility of Monte Carlo modeling lies in shuffling the sequence of drawdowns and recoveries to evaluate whether your capital base possesses enough structural redundancy to withstand a retirement that launches directly into a bear market. This framework forms the quantitative foundation of the operational rules detailed in The FIRE Cash-Flow Kill Line and the Three-Tier Reserve Defense Architecture.
3. The 5-Step Actuarial Protocol for Quantifying Personal FIRE Thresholds
Quantifying an individual FIRE number—the absolute investable liquid capital required to permanently exit wage labor—requires a structured five-step actuarial protocol:
| Protocol Stage | Core Parameters & Execution Mechanics | Real-World Empirical Calibration |
|---|---|---|
| 1. Anchor Net Deficit & Horizon | Initial annual net withdrawal (total gross burn minus stable passive cash flows) across the total projected retirement horizon. | Exiting the workforce between ages 35 and 45 requires planning for a 40- to 50-year horizon—far more unforgiving than the 30-year span assumed by traditional models. |
| 2. Define Asset Allocation & Volatility (σ) | Proportions of global equities, sovereign debt, and cash equivalents; projected real returns (μ) and annualized portfolio standard deviation (σ). | Single-country emerging market or concentrated equity portfolios carry annualized volatilities of 18%–22%, compared to ~14%–15% for broad global indices, driving down survival rates at equivalent withdrawal rates. |
| 3. Inject Stochastic Shocks & Fat Tails | Execute 1,000 to 10,000 randomized iterations adjusting purchasing power against shifting inflation corridors and asset price swings. | Advanced frameworks incorporate fat-tail shocks or historical block bootstrapping to capture concurrent black-swan equity collapses and stagflationary regimes. |
| 4. Map Survival Probability to SWR | Calculate the percentage of paths maintaining capital > 0 at year 40, back-solving for the principal needed to secure a 90%–95% confidence corridor. | If extracting $35,000 annually from a $1,000,000 asset base (3.5% SWR) yields 9,200 solvent outcomes across 10,000 iterations over 40 years, the portfolio survival rate is 92.0%. |
| 5. Integrate Cash Cushions & Guardrails | Implement algorithmic defensive rules: freeze equity sales during market pullbacks to draw from cash; cut discretionary burn by 15% during deep drawdowns. | Dynamic guardrails decouple spending from depressed equity markets, drastically improving long-term portfolio survival without demanding millions in surplus initial capital. |
When auditing balance sheets, particularly among affluent households across transitioning economies, a common structural vulnerability emerges: families often hold substantial theoretical net worth, but upwards of 70% remains locked inside illiquid real estate with low rental yields. The true investable, cash-flow-generating net worth rarely exceeds 30% of their total balance sheet. When executing Steps 1 and 2, primary residential equity must be excluded; only liquid, yielding assets can serve as the baseline for Monte Carlo modeling.
4. Three Empirical Dictums from 10,000 Stochastic Iterations
Translating the output of tens of thousands of Monte Carlo trials into actionable financial engineering yields three counterintuitive rules of thumb:
1. Discard the Mechanical “4% Rule”—Target a 3.3% to 3.5% SWR
The popular “4% Rule” (accumulating 25 times your annual expenditure) stems from William Bengen’s 1994 paper and the subsequent Trinity Study. Both works relied on two specific historical conditions: a structural multi-decade tailwind in 20th-century US capital markets, and a finite 30-year horizon (retiring at 65, planning to age 95).
If you retire between ages 35 and 45, your capital base must withstand 40 to 50 years of inflationary pressure, geopolitical shifts, and deep economic cycles. Under these conditions, running a mechanical 4.0% withdrawal rate drops 40-year portfolio survival below 75%. For early retirees, compressing the initial safe withdrawal rate to 3.2%–3.5%—accumulating 28.5 to 31 times net annual expenditure—is the baseline required to clear a 90%+ actuarial confidence threshold.
2. Quantify the Asymmetric Leverage of an Independent Cash Cushion
Pursuing an unhedged 99% survival rate solely by depressing withdrawal rates forces individuals to save 40 to 50 times their annual burn, condemning them to indefinite corporate servitude.
The mathematical escape from this trap is the combination of an isolated cash cushion and dynamic guardrails:
- Segregated Liquidity Pool: Maintain 24 to 36 months of net living expenses in high-yield money market funds or short-duration sovereign bills, kept separate from the risk portfolio. In positive return years, living costs are withdrawn directly from investment profits, replenishing the cash pool. During negative return years, freeze equity liquidations entirely, funding all living expenses directly from the cash cushion.
- Dynamic Expenditure & Geographic Arbitrage: As analyzed in The Dual-Engine Playbook: Digital Nomads vs. FIRE, introducing a simple operational rule—reducing discretionary spend by 15% or shifting to lower-cost hubs via seasonal migration during portfolio drawdowns exceeding 15%—lifts a portfolio with an initial ~70% baseline survival rate to over 94%–96%.
5. The FIREways Dual-Engine FIRE Calculator: Architecture and Playbook
To remove the friction of writing customized Python scripts to stress-test your balance sheet, FIREways developed and launched a real-time bilingual actuarial tool: The FIREways Financial Independence & Nomadic Longevity Calculator.
1. Why a Dual-Engine Architecture?
Standard retirement calculators generally suffer from one of two flaws: they present a single, smoothed compounding line that breeds ungrounded optimism, or they present an abstract Monte Carlo probability without showing how cash reserves are depleted during early bear markets.
The FIREways Calculator runs two complementary engines simultaneously, re-rendering outcomes within 3 milliseconds of any parameter adjustment:
Engine 1: 40-Year Deterministic SORR Stress Engine Specifically targeting the vulnerable “first three years” of retirement, this module provides instant toggling between three deterministic stress scenarios: Severe Early Bear Market (consecutive annual real returns of -18%, -12%, and -5%), Mild Early Chop (-10%, -6%), and a Stable Compounding Baseline. It plots both the “Cash-Cushioned Trajectory” and the “Zero-Buffer Unhedged Trajectory” on a single axis, charting annual reserve drawdowns and recoveries.
Engine 2: 1,000-Run Stochastic Monte Carlo Engine Powered by a deterministic pseudo-random number generator (Mulberry32 PRNG) paired with the Box-Muller transform and a 6% fat-tail black swan probability, this engine generates 1,000 distinct 40-year asset paths directly in your browser based on your portfolio’s annualized volatility (σ: 4%–25%). It automatically applies cash-buffer guardrails across every path, calculating the 40-Year Survival Rate, contrasting it against an unhedged baseline, and rendering a P10–P75 confidence corridor behind the primary forecast.
2. A 3-Step Guide to Stress-Testing Your FIREways Plan
- Select a Lifestyle Preset or Customize Cash Flows: Open the FIREways Calculator and choose a baseline persona (e.g., “Southeast Asian Nomadic Lean FIRE,” “Global Wellness & Golf Coast FIRE,” or “Tier-1 Metro Fat FIRE”), or adjust the sliders to match your target monthly expenditure and nomadic baseline income.
- Calibrate Real Returns and Portfolio Volatility (σ): Input your liquid investable assets, annual savings additions, SWR (target: 3.5%), and portfolio volatility (12%–15% for globally diversified equity/debt mixes; 18%–20% for concentrated single-country equities).
- Compare “Zero vs. 2-Year Cash Buffer” Outcomes: Toggle the cash cushion slider to directly observe how your 1,000-Run Monte Carlo Survival Rate transitions from a fragile posture into an antifragile, 90%+ confidence zone. Expand the 40-Year Milestone Balance Ledger below the chart to verify your purchasing power across every decade.
6. Synthesis and Actuarial Verdicts
Financial independence is not a static net worth metric; it is a dynamic cash-flow architecture engineered to absorb volatility shocks without cannibalizing core capital. When probabilistic modeling and cash-flow guardrails replace crude rules of thumb, the anxiety of early retirement resolves into quantifiable, manageable parameters.
Actuarial Summary
- Verdict 1 (The Primacy of Sequence Risk): Over a 30- to 50-year withdrawal phase, the chronological sequence of returns (SORR) exerts far greater control over survival than the multi-decade arithmetic mean. Entering retirement into a three-year bear market without an independent cash buffer forces structural asset liquidations at cyclical lows, driving portfolios to premature depletion regardless of later rallies.
- Verdict 2 (The Fallacy of the Generic 4% Rule): The conventional “4% Rule” assumes a short 30-year retirement backed by specific historical conditions. For early retirees navigating a 40- to 50-year span, incorporating realistic volatility and fat-tailed shocks drops the survival rate of an unhedged 4.0% withdrawal strategy below 75%.
- Verdict 3 (The Defensive Prescription): Anchoring safe withdrawal rates between 3.3% and 3.5%, establishing an isolated 24- to 36-month cash cushion, and integrating dynamic lifestyle guardrails through geographic arbitrage reliably locks in 40-year Monte Carlo survival rates above 92% to 96%. Readers can stress-test their personal financial position directly using the FIREways Financial Independence & Nomadic Longevity Calculator.
⛳ Further Exploration: The FIREways Nomadic Society
Looking beyond the urban corporate treadmill? FIREways connects long-term practitioners focused on Geographic Arbitrage, Cash-Flow Antifragility, and Nomadic Living:
- 🏡 Curated Long-Stay Residencies: Negotiated seasonal rates across premier wellness and lifestyle hubs throughout Hainan, Yunnan, Chiang Mai, Johor, and Kyushu;
- 🤝 Peer Masterminds: Dedicated exchanges with digital nomads, FIRE practitioners, and sovereign solopreneurs;
- 📊 Actuarial Field Ledgers: Real-world operating budgets, cross-border tax architectures, and asset structuring playbooks.
👉 Return to the FIREways Homepage to explore the full archive
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。