Beyond the Territorial Refuge: Costa Rica’s 15% Foreign Income Tax and the Financial Trajectory of Nomadic Capital
Costa Rica's Ministry of Finance has introduced Bill N.° 25.796, aiming to levy a 15% tax on foreign-sourced passive income for tax residents staying over 183 days. Intersecting with OECD automatic information exchange networks, this legislative shift dismantles the illusion of friction-free geo-arbitrage and redefines cross-border asset compliance.

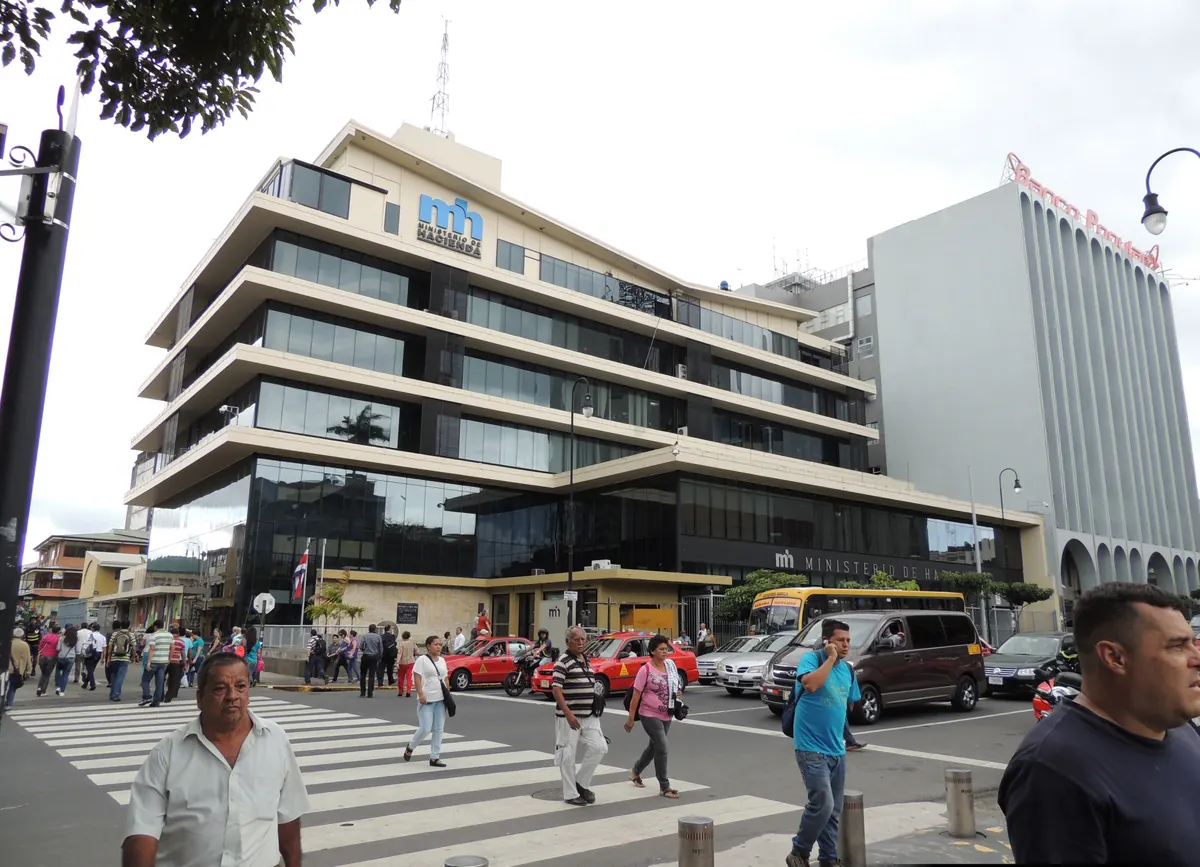
Figure 1: The Ministry of Finance (Ministerio de Hacienda) in San José. The newly submitted bill disrupts traditional offshore tax exemption expectations.
The formal submission of Bill Expediente N.° 25.796 by Costa Rica’s Ministry of Finance to the Legislative Assembly—proposing a flat 15% tax on foreign-sourced interest, dividends, capital gains, royalties, and rental income for tax residents—has sent shockwaves through Latin America’s expatriate community. For decades, Costa Rica relied on its strict territorial tax system and pristine eco-infrastructure to market itself as a natural harbor for digital nomads and early retirees pursuing Financial Independence, Retire Early (FIRE). However, squeezed between OECD anti-tax-avoidance mandates and escalating domestic fiscal deficits, the era of extinguishing global capital taxation simply by relocating one’s physical body across borders is rapidly reaching its structural conclusion.
Erosion of the Territorial Fortress: Dissecting the Scope of Bill N.° 25.796
Positioned between the Caribbean Sea and the Pacific Ocean, Costa Rica built an enviable reputation among mobile high-net-worth individuals due to its legacy tax architecture. Under its traditional income tax laws, the country operated under a strict territorial principle: regardless of nationality or residency status, the state exercised tax jurisdiction solely over income generated within or derived from economic activity inside Costa Rica (Source of Income). Offshore investment portfolios, foreign dividend distributions, and cross-border consulting revenues remained systematically outside the reach of the local tax authority. This framework drew tens of thousands of location-independent professionals and retirees from North America, Europe, and East Asia.
The legislative proposal introduced by the Ministry of Finance (Ministerio de Hacienda)—officially titled the Draft Law on the Taxation of Foreign-Source Passive Income and the Elimination of Tax Credits for the Issuance of Publicly Offered Thematic Securities (Ley sobre el gravamen de rentas pasivas de fuente extranjera y eliminación de créditos fiscales por la emisión de valores de oferta pública temáticos)—signals a decisive departure from this historical paradigm.
The core modifications target the foundational jurisdictional logic of the Income Tax Law (Ley del Impuesto sobre la Renta). Rather than recklessly pivoting toward an aggressive worldwide income tax model akin to that of the United States, the bill precisely targets foreign passive capital income (rentas pasivas de capital de fuente extranjera). Specifically, it proposes a flat 15% income tax on five distinct categories of passive investment returns accrued outside Costa Rica:
- Foreign Investment Interest (Intereses): Interest derived from foreign bank deposits, offshore bonds, and private lending agreements;
- Dividends from Foreign Entities (Dividendos): Dividend payouts yielded through equity holdings in U.S., European, or offshore brokerage accounts;
- Foreign Capital Gains (Ganancias de capital): Realized capital appreciation from trading foreign equities, ETFs, investment fund shares, and real property;
- Foreign Intellectual Property Royalties (Regalías): Licensing fees generated from offshore software copyrights, patents, and trademarks;
- Foreign Real Estate Rents (Alquileres): Rental yields harvested from investment properties located in an individual’s origin country or third-party jurisdictions.
This legislative pivot is not an isolated phenomenon. Much like Thailand’s overhaul of foreign income remittance rules and its LTR visa defense, nations that historically championed territorial taxation are swiftly patching regulatory loopholes surrounding foreign passive capital flows under mounting scrutiny from international regulatory bodies.
Crucially, the Costa Rican proposal leaves protections for active earned income intact. Wages paid by foreign employers to expatriate employees, service fees for cross-border professional services, and formal public pension distributions (such as foreign social security benefits) are explicitly excluded from the 15% passive income levy. Furthermore, the bill introduces a foreign tax credit mechanism (Tax Credit). If a taxpayer has already paid income tax in the source country, they may apply for a credit up to the amount of local tax liability. However, for assets parked in zero-tax or nominal-tax jurisdictions such as the Cayman Islands or the British Virgin Islands—where proof of substantive foreign tax payment is absent—triggering Costa Rican tax residency will expose the underlying yields to the full 15% top-up tax.
Residency Thresholds and Transparency: How the 183-Day Line Intersects with CRS
The primary source of anxiety among international residents stems from how the bill defines tax subjectivity. Under the text of Expediente N.° 25.796, the law directly adopts the standard definition of “Costa Rican Tax Resident (Residencia Fiscal)” as the controlling jurisdictional benchmark.
Under Costa Rican tax jurisprudence, tax residency adheres to the standard physical presence test: any natural person residing within Costa Rican territory for an aggregate of more than 183 days during a given tax year (calendar year)—whether continuously or intermittently—automatically acquires legal tax residency. This rule encompasses individuals, local legal entities, trusts (fideicomisos), and private investment funds. More critically, the proposal dismantles previous restrictions that limited scrutiny strictly to “offshore shell companies affiliated with multinational groups lacking economic substance,” extending the scope directly to all personal offshore financial assets held by long-term resident individuals.
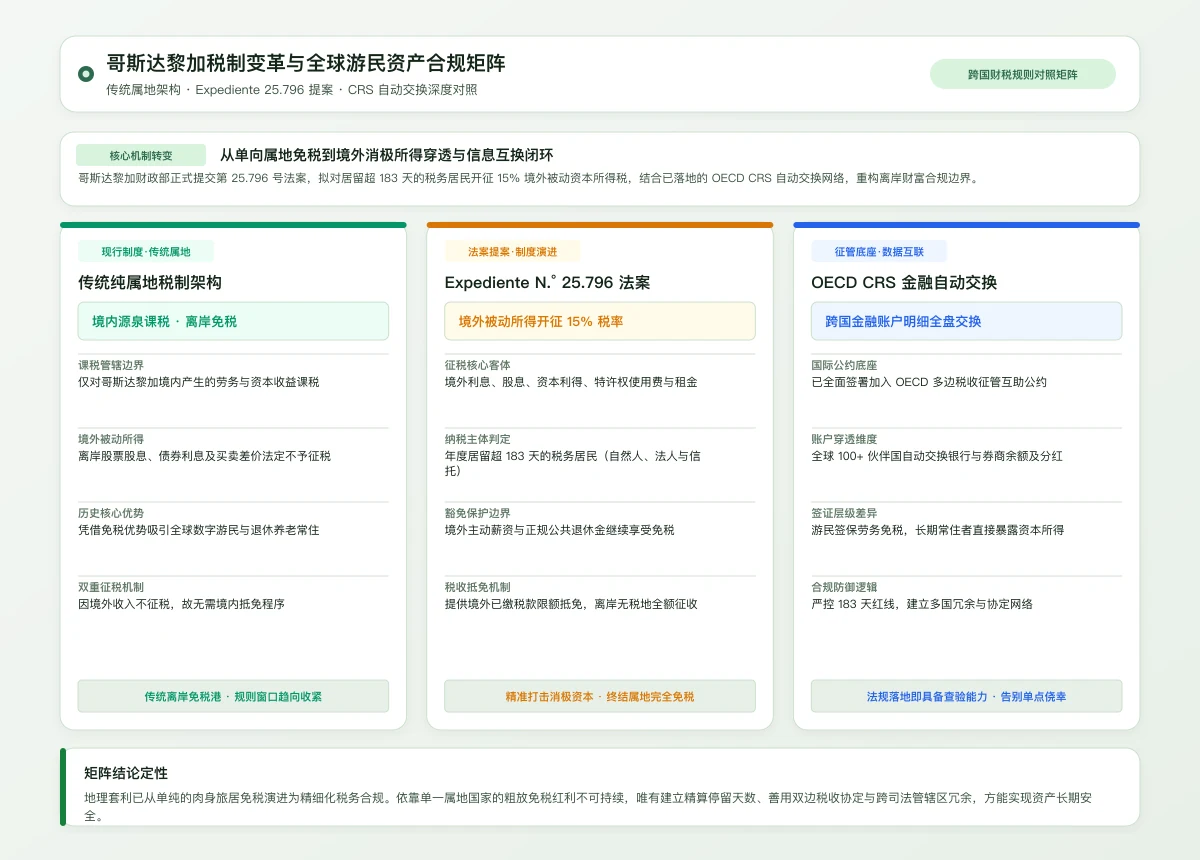
Figure 2: Comparative analysis between Costa Rica’s legacy territorial tax system and the key provisions of Bill Expediente N.° 25.796.
Many digital nomads operate under the misconception that holding a specific immigration permit renders them immune to local tax obligations. In reality, immigration status and tax residency exist on distinct legal planes:
- Digital Nomad Visa (Ley N° 10008): Enacted in 2021, Costa Rica’s remote worker visa explicitly grants holders exemption from local personal income tax for one year (renewable for a second year). However, this statutory relief was engineered specifically for remote earned income derived from foreign employers or clients. It was never intended as a blanket shield against tax liability on substantial capital gains and dividend income generated after establishing long-term residence;
- Pensioner (Pensionado) and Investor (Inversionista) Residencies: Holders of these long-term residency tracks almost universally breach the 183-day physical threshold. Historically, these residents enjoyed Caribbean sunshine in San José while receiving tax-free cash flows from US equities and offshore wealth management accounts. If the bill passes, these passive portfolios will be subject to mandatory reporting and taxation.
While statutory amendments establish the legal right to tax, the global infrastructure for automatic tax information exchange provides the revenue authority with direct insight into underlying asset holdings. Costa Rica ratified the OECD Multilateral Convention on Mutual Administrative Assistance in Tax Matters years ago and fully operationalized the Common Reporting Standard (CRS).
Consequently, the Directorate General of Taxation (Dirección General de Tributación) maintains active channels for exchanging financial account information with over 100 jurisdictions. Once a resident provides a Costa Rican residential address or local tax identification number (NITE/DIMEX) to a foreign bank or brokerage, year-end account balances, interest earned, dividend distributions, and gross proceeds from securities sales are automatically aggregated by foreign financial institutions and transmitted to Costa Rican tax authorities.
As highlighted in analysis of Portugal’s Golden Visa dynamics and CRS cross-border tax audits, technical capabilities in tax administration long ago breached sovereign borders. The assumption that local tax authorities cannot track offshore brokerage accounts is obsolete in an era governed by systemic CRS automation.
Institutional Evolution: Comparing the Current Territorial System with Bill N.° 25.796
To illustrate the concrete shifts expected should this bill pass into law, the table below outlines the core differences between Costa Rica’s current tax code and the proposed provisions of Expediente N.° 25.796:
| Assessment Dimension | Current Tax Code (Pure Territorial) | Bill N.° 25.796 Proposal | Practical Impact on Nomads & Expatriates |
|---|---|---|---|
| Tax Jurisdictional Scope | Domestic-source income only | Domestic income + Foreign passive capital income | Offshore investment asset yields brought under tax scope for the first time |
| Foreign Passive Tax Rate | Exempt by default (outside scope) | Flat 15% rate | US stock dividends, bond interest, and realized trading gains become taxable |
| Primary Target Audience | Local entities and local service providers | Tax residents staying >183 days (including natural persons) | Long-stay digital nomads and retirees directly exposed |
| Active Labor & Pensions | Foreign labor and foreign pensions exempt | Foreign labor and foreign pensions remain exempt | Pure remote worker salaries remain temporarily protected |
| Double Taxation Relief | N/A (foreign income was untaxed) | Foreign tax credit mechanism provided (subject to caps) | Assets in jurisdictions with tax rates under 15% or zero-tax zones must pay the difference |
| Audit Infrastructure Support | Limited mechanisms for auditing foreign assets | Integrated with existing OECD CRS automatic exchange network | Tax agency can cross-reference offshore bank/brokerage data with local tax filings |
Viewed through a macroeconomic lens, Costa Rica’s policy shift is predictable. As an OECD member state, Costa Rica faces constant pressure from the EU Code of Conduct Group regarding Foreign Source Income Exemption (FSIE) regimes, compelling it to prevent foreign residents from exploiting territorial rules for zero-tax offshore profit shifting. Simultaneously, burdened by persistent public fiscal deficits, the government is eager to unlock stable revenue streams targeting affluent resident demographics.
Defensive Architecture for Geo-Arbitrageurs: From Physical Evasion to Structural Redundancy
For global citizens relying on geo-arbitrage to navigate cross-border living and capital allocation, Costa Rica’s legislative initiative serves as a clear indicator: the playbook of relying on a single country’s low-tax or tax-free grace is rapidly sunsetting. Primary destination countries worldwide are tightening regulatory controls over passive cross-border capital to satisfy international compliance standards and bolster domestic treasuries.
In response to this systemic realignment, individuals seeking long-term asset preservation and personal autonomy must rebuild their compliance architecture across three key dimensions:
1. Actively Managing Residency Triggers via Day-Count Engineering
The 183-day threshold functions as a strict legal boundary. For highly mobile individuals who have not committed heavy capital to local real estate and rely primarily on flexible leases, the most cost-effective response is proactive day-count management.
By engineering a multi-nodal, migratory lifestyle strategy—restricting annual stay durations in any single jurisdiction to between 90 and 120 days—individuals can prevent the legal triggers of tax residency from taking hold. This strategy requires maintaining an auditable paper trail of physical presence through passport stamps, flight itineraries, and short-term lease agreements, providing robust evidentiary defense against tax residency claims from any single jurisdiction.
2. Bifurcating Active and Passive Cash Flows & Leveraging Tax Treaties
For long-term residents who intend to acquire physical real estate in Costa Rica, enroll dependents in local schools, or settle permanently, a fundamental restructuring of balance sheets and cash flow streams is necessary.
First, operational cash flows supporting daily living should be aligned with categories eligible for territorial exemptions—such as active technical consulting fees or qualifying foreign pension streams—reducing reliance on high-frequency offshore trading gains and un-credited dividend flows. Second, individuals must audit the Double Taxation Agreement (DTA) network between their asset-holding jurisdictions and Costa Rica to ensure withholding taxes paid at the source yield valid tax credits, fully offsetting local 15% liabilities.
The multi-tiered structural frameworks detailed in analysis of the Cyprus non-domiciled tax framework and pension compliance paths offer a valuable reference. Utilizing recognized non-domiciled (Non-Dom) regimes and treaty networks provides a legal mechanism to mitigate double taxation exposure.
3. Abandoning Single-Point Dependencies: Building Jurisdictional Redundancy
The fundamental premise of geo-arbitrage has never been about discovering an enduring tax haven; it is about refusing to anchor one’s life, wealth, and legal standing to the policy benevolence of a single sovereign state. The introduction of Expediente N.° 25.796 demonstrates that immigration rules and tax incentives can pivot rapidly under shifting political coalitions, fiscal distress, or international regulatory pressure.
A resilient international strategy requires systemic redundancy across jurisdictions: secondary residency rights, offshore capital distributed across rule-of-law jurisdictions that refrain from retroactive taxation, and operational mobility to transition base locations when underlying conditions change. By moving past a reliance on single-country tax exemptions and structuring assets through legal frameworks, mobile individuals can continue to protect their financial independence and personal autonomy within an increasingly transparent global tax ecosystem.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。