The Collapse of CreditEase: A Forensic Audit of Wealth Management Risk
An analytical deep-dive into the 2026 collapse of CreditEase and the criminal indictment of Tang Ning. This report deconstructs the anatomy of 'quasi-fixed income' Ponzi schemes and provides a five-step forensic audit guide for investors to identify and mitigate systemic wealth risks.

Executive Summary: On October 12, 2026, the Chaoyang Branch of the Beijing Public Security Bureau issued a formal notice confirming the criminal investigation into CreditEase and its affiliates. Tang Ning, the firm’s founder and actual controller, alongside his spouse Zhao Mei, have been placed under criminal coercive measures. Once a titan of China’s fintech and independent wealth management sector, CreditEase’s “Ruicheng Wealth” division—a massive pool of quasi-fixed income products—collapsed after a five-month liquidity freeze, culminating in an admission of insolvency and illegal fundraising. This report reconstructs the collapse, debunks persistent myths regarding the founder’s political lineage, dissects the five fatal traps of non-standard wealth products, and provides a rigorous, five-step diagnostic framework for investors.
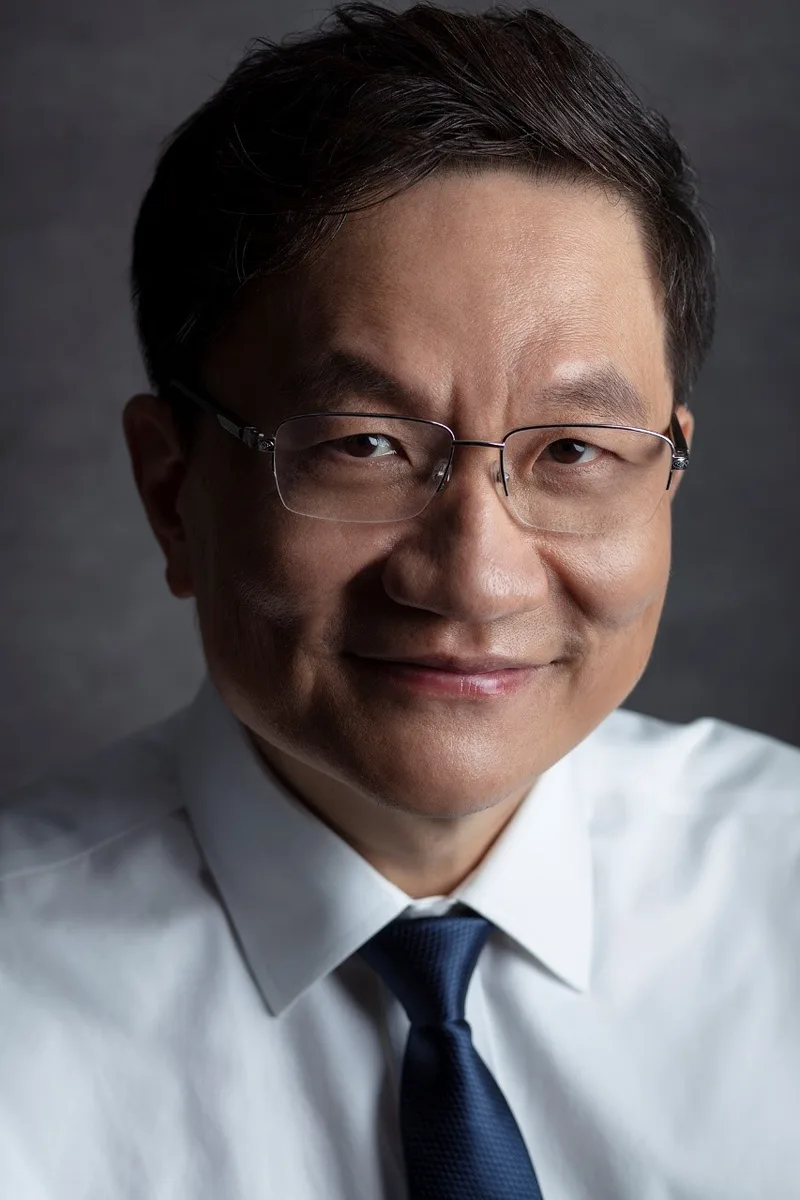
Figure 1: Tang Ning, Founder of CreditEase
I. The Anatomy of a Collapse: From “Orderly Exit” to Insolvency
CreditEase, a pioneer in China’s fintech landscape, saw its multi-year “quasi-fixed income” asset pool unravel in the autumn of 2026, transitioning from a corporate liquidity crisis to a criminal judicial proceeding.
1. Chronology of the Collapse
The trajectory of CreditEase mirrors the classic “four-stage collapse” observed in previous large-scale non-standard wealth management failures:
- Phase 1: Liquidity Fracture (May 22, 2026) CreditEase’s core wealth management matrix (including Ruicheng Wealth and Yiren Youxuan) halted all principal and interest payments. Tang Ning issued a company-wide letter announcing an “orderly exit,” promising a resolution plan to pacify investors and buy time for asset liquidation.
- Phase 2: Stalling and Public Admission (October 11, 2026) After five months of stagnation, CreditEase pushed an apology via its app. Management admitted that off-balance-sheet investments had suffered catastrophic losses, and market-based asset recovery was far below expectations. A third-party audit confirmed the group was technically insolvent, with a massive gap in liabilities.
- Phase 3: Criminal Indictment (October 12, 2026) The day following the apology, the Beijing Public Security Bureau announced a formal investigation into CreditEase for suspected illegal fundraising. Tang Ning (53) and his spouse Zhao Mei (51) were taken into custody.
2. Scale and Victim Profile
Estimates suggest the outstanding volume of frozen quasi-fixed income products ranges between 30 billion and 50 billion RMB, affecting nearly 100,000 investors. Unlike early P2P retail investors, the victims here are high-net-worth individuals, SME owners, and retired executives, with entry thresholds typically between 1 million and 5 million RMB. This collapse marks the final chapter of the “trillion-yuan” third-party wealth management myth, following the implosions of Zhongzhi and Haiyin Wealth.
II. Debunking the “Political Lineage” Myth
During the crisis, rumors circulated that Tang Ning was the son of former State Councilor Tang Jiaxuan. Forensic verification of public records and judicial filings confirms this is entirely baseless.
1. Comparative Dossier
| Dimension | Tang Jiaxuan (Former Official) | Tang Ning (CreditEase) |
|---|---|---|
| Birth/Origin | 1938, Zhenjiang, Jiangsu | 1973, Beijing |
| Education | Fudan/Peking University (Foreign Languages) | Peking University (Math) / University of the South (USA) |
| Career Path | Diplomatic Service / Foreign Minister | Wall Street Analyst / VC / Founder of CreditEase |
| Legal Status | Retired State Leader | Subject of criminal investigation |
2. The Psychology of False Endorsement
Why do such myths persist?
- Information Asymmetry: In the absence of transparent, audited underlying assets, investors rely on “implicit guarantees” and perceived political protection.
- Sales Collusion: Wealth managers often weaponize these rumors, using the “untouchable background” narrative to close seven-figure deals when clients express doubt.
- The Reality of Law: The criminal measures taken against Tang Ning prove that no amount of fabricated political capital can override the physical laws of a broken balance sheet.
III. Five Fatal Traps of Non-Standard Wealth Products
The products that fueled these collapses share a common, toxic structure. Any product exhibiting these traits is likely operating on the edge of a legal and liquidity cliff:
| Risk Type | Mechanism of Deception | Fatal Flaw |
|---|---|---|
| Pseudo-Exchange Products | Marketed as “Financial Asset Exchange” filings. | These are unregulated, off-balance-sheet fundraising vehicles. |
| “Quasi-Fixed Income” Pools | Packaged as private equity but promising 6-10% yields. | Classic maturity mismatch; “robbing Peter to pay Paul.” |
| Self-Dealing/Nesting | Complex LP/GP structures controlled by the same entity. | “Left hand to right hand” transfers to cover bad debts. |
| “Equity-in-Name, Debt-in-Fact” | Guaranteed buybacks disguised as equity investments. | The “guarantor” is usually an empty shell. |
| Offshore Non-Standard Debt | Claims of “Global Asset Allocation.” | Exposure to junk bonds in legal/jurisdictional vacuums. |
IV. The Five-Step Forensic Self-Audit
If you hold products from third-party wealth managers, do not rely on marketing brochures. Use this diagnostic tree:
- Verify the Counterparty: If the payment recipient is a wealth management firm or an individual, rather than a licensed “Fund Custody Account,” it is likely illegal fundraising.
- Check Regulatory Filings: Cross-reference the product code on the Asset Management Association of China (AMAC) website. If the manager or product name doesn’t match your contract, it is a fraud.
- Audit Underlying Assets: Are there real, registered liens on assets? If the “collateral” is only a promise on paper, it is worthless.
- Assess Maturity Mismatch: If the product offers short-term liquidity (1 year) but invests in long-term, illiquid assets (real estate/distressed debt), it is a Ponzi structure.
- Secure Evidence: Export all digital contracts, transfer records, and chat logs (especially those mentioning “guaranteed returns”). Avoid “recovery agents” who promise to unlock funds for a fee—these are secondary scams.
V. Conclusion: The New Margin of Safety
The era of “guaranteed” non-standard wealth management is over. When the underlying return on assets cannot cover the promised yield, the structure is a liquidity illusion waiting to shatter. For the modern investor, the only path to safety is the abandonment of opaque, high-yield traps in favor of transparent, regulated, and independently custodied assets. The “speed of growth” is irrelevant if the “principal” is destined for zero.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。