The Defensive Architecture of Localized FIRE: An Evidence-Based Playbook for the High-Efficiency Life
A deep dive into the 'HowToLiveBetter' framework, reframing FIRE for the Chinese context through six dimensions of systemic defense, from social security continuity to legal risk mitigation.

Executive Summary: Western FIRE (Financial Independence, Retire Early) theory is often predicated on a “greenhouse” environment: the long-term annualized returns of the S&P 500, the 4% withdrawal rule, and robust commercial insurance. However, practicing FIRE in China is less about hitting a 25x spending target and more about surviving the “de-institutionalization” process. Without the safety net of a corporate or state employer, one faces medical insurance waiting periods, the collapse of “guaranteed” financial returns, and legal traps that can liquidate a lifetime of savings. The open-source project HowToLiveBetter provides a hardcore, evidence-based toolkit—stripped of get-rich-quick fantasies—to build a resilient safety net for the modern nomadic professional.
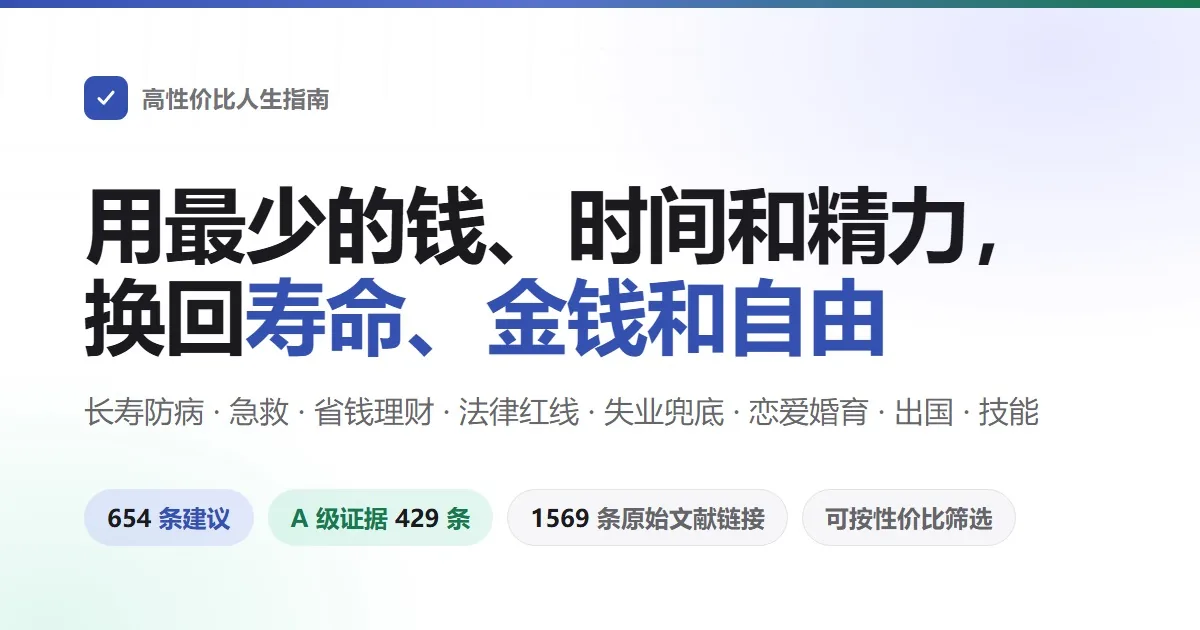
Figure 1: The ‘HowToLiveBetter’ project utilizes peer-reviewed journals and current regulations as its sole sources to construct a decision-making dictionary for high-certainty living.
I. Cognitive Demystification: A Non-Perfectionist Menu of Efficiency
The open-source project HowToLiveBetter, initiated by GitHub developer eternity4719, has resonated deeply within the Chinese tech community. Its appeal lies in its rejection of traditional self-help empiricism and emotional platitudes. Instead, it applies rigorous engineering and epidemiological logic to calculate the “Return on Investment” (ROI) of life choices.
1. The Physical Boundaries of Ultimate Assets
The guide begins by refusing to reduce everything to currency. It identifies four core, non-fungible assets:
- Longevity: Staying alive and healthy; avoiding preventable premature death and the attrition of metabolic or cardiovascular chronic diseases.
- Time & Energy: Minimizing the theft of cognitive resources by systemic noise and inefficient internal friction.
- Capital: Plugging the leaks of consumerism, high-interest financial scams, and rigid debt to maintain a liquidity floor.
- Personal Liberty: Navigating the red lines of administrative and criminal law to avoid becoming a “discredited person” or a defendant due to cognitive blind spots.
2. The Rigor of Evidence-Based Grading
The guide contains over 650 recommendations, strictly excluding “lifestyle influencer” advice or second-hand media. It relies on two primary sources: Top-tier peer-reviewed journals (with DOI/PubMed IDs) and current national laws and official policy documents. Entries are graded by strength of evidence:
- Grade A (60%+): Derived from multi-center Randomized Controlled Trials (RCTs), meta-analyses of prospective cohort studies, or explicit legal statutes.
- Grade B: Supported by rigorous academic research but with limited sample sizes or lack of precise hazard ratio quantification.
- Grade C: Authoritative industry consensus or general rules of thumb where double-blind data is unavailable.
- Academic Dispute Markers: Entries with scholarly disagreement (e.g., specific nutrient upper limits or false-positive rates in screenings) list opposing evidence and boundary conditions.
3. The 34-Chapter Scenario Matrix
The framework spans the entire lifecycle—from youthful exploration to aging and estate settlement—across six dimensions:
| Core Dimension | Key Chapters & Real-World Issues |
|---|---|
| Health & Prevention | 01. Avoiding Premature Death; 02. Avoiding “Slow Death” (quantifying smoking/alcohol/sleep deprivation); 16. Living with Chronic Illness; 24. Navigating Healthcare Costs; 34. Home Medication Safety |
| Efficiency & Mindset | 03. Conserving Energy (attention isolation); 04. Conserving Time (implementation intentions); 22. Scientific Relaxation; 29. Crisis Response (coping with bereavement, job loss, or diagnosis) |
| Finance & Pitfalls | 05. Avoiding Monetary Waste (passive indexing, anti-fraud, fee transparency); 06. The “Negative List” (IQ-tax supplements); 07. Survival on Low Income (unemployment benefits, wage recovery); 15. Housing Law |
| Legal & Security | 08. Property Security (pre/post-nuptial rights, transfer risks); 09. Common Legal Red Lines (information crimes); 11. Tech Worker Risks (crawler compliance, gambling/porn outsourcing); 12. Entrepreneurial Firewalls |
| Family & Legacy | 10. The Economics of Marriage (legal contracts); 17. Elder Care (guardianship, wills); 18. The Opportunity Cost of Childrearing; 25. Post-Mortem Procedures (pension extraction without notarization) |
| Emergency & Planning | 13. Immediate Crisis (CPR/AED/Hemorrhage); 14. Info Security (2FA, account recovery); 19. Employment Exit (N+1 compensation, leave encashment); 23. High-ROI Skills; 33. Living with Disability |
The author emphasizes: This is a menu of options, not a KPI checklist. One does not need to follow every rule; rather, when facing a life crossroads, one can pull a specific lever to avoid a catastrophic outcome.
II. Reframing the Perspective: Why Localized FIRE Requires a “Defensive Toolkit”
As analyzed in our previous work on Taoist Philosophy and Modern FIRE, the essence of modern FIRE is the exchange of one’s youth—depreciated within a high-intensity social machine—for a portfolio of cash-flow-generating assets. It is an attempt to “buy out the system.”
However, this buyout remains contingent. Your food, healthcare, and purchasing power are tethered to institutional frameworks and financial conduits.
In the Western narrative, FIRE is often mechanical:
Accumulate 25x annual expenses ➔ Invest in S&P 500 ➔ Withdraw 4% annually.
In the Chinese context, this model hits several “hidden reefs”:
- Divergent Financial Markets: The absence of a multi-decade secular bull market in domestic indices; the collapse of “guaranteed” returns in wealth management products; and the prevalence of high-yield traps.
- Institutional Fault Lines: Once you sever the employer-employee relationship, how do you bridge medical insurance? How do you mitigate the “waiting period” for benefits after a lapse in payment?
- Unlimited Legal Liability: In a high-trust social network or partnership, a single “joint and several liability” signature can lead to the seizure of all assets by court order, erasing decades of savings instantly.
- One-Way Biological Attrition: Early retirees often face a physiological inflection point. A preventable chronic illness or accident, without the moat of basic medical insurance and tiered diagnosis, can breach the 4% withdrawal model within months.
For the localized FIRE practitioner, HowToLiveBetter is not just a health guide; it is a defensive construction manual designed to plug wealth black holes and ensure the survival net remains intact without an employer.
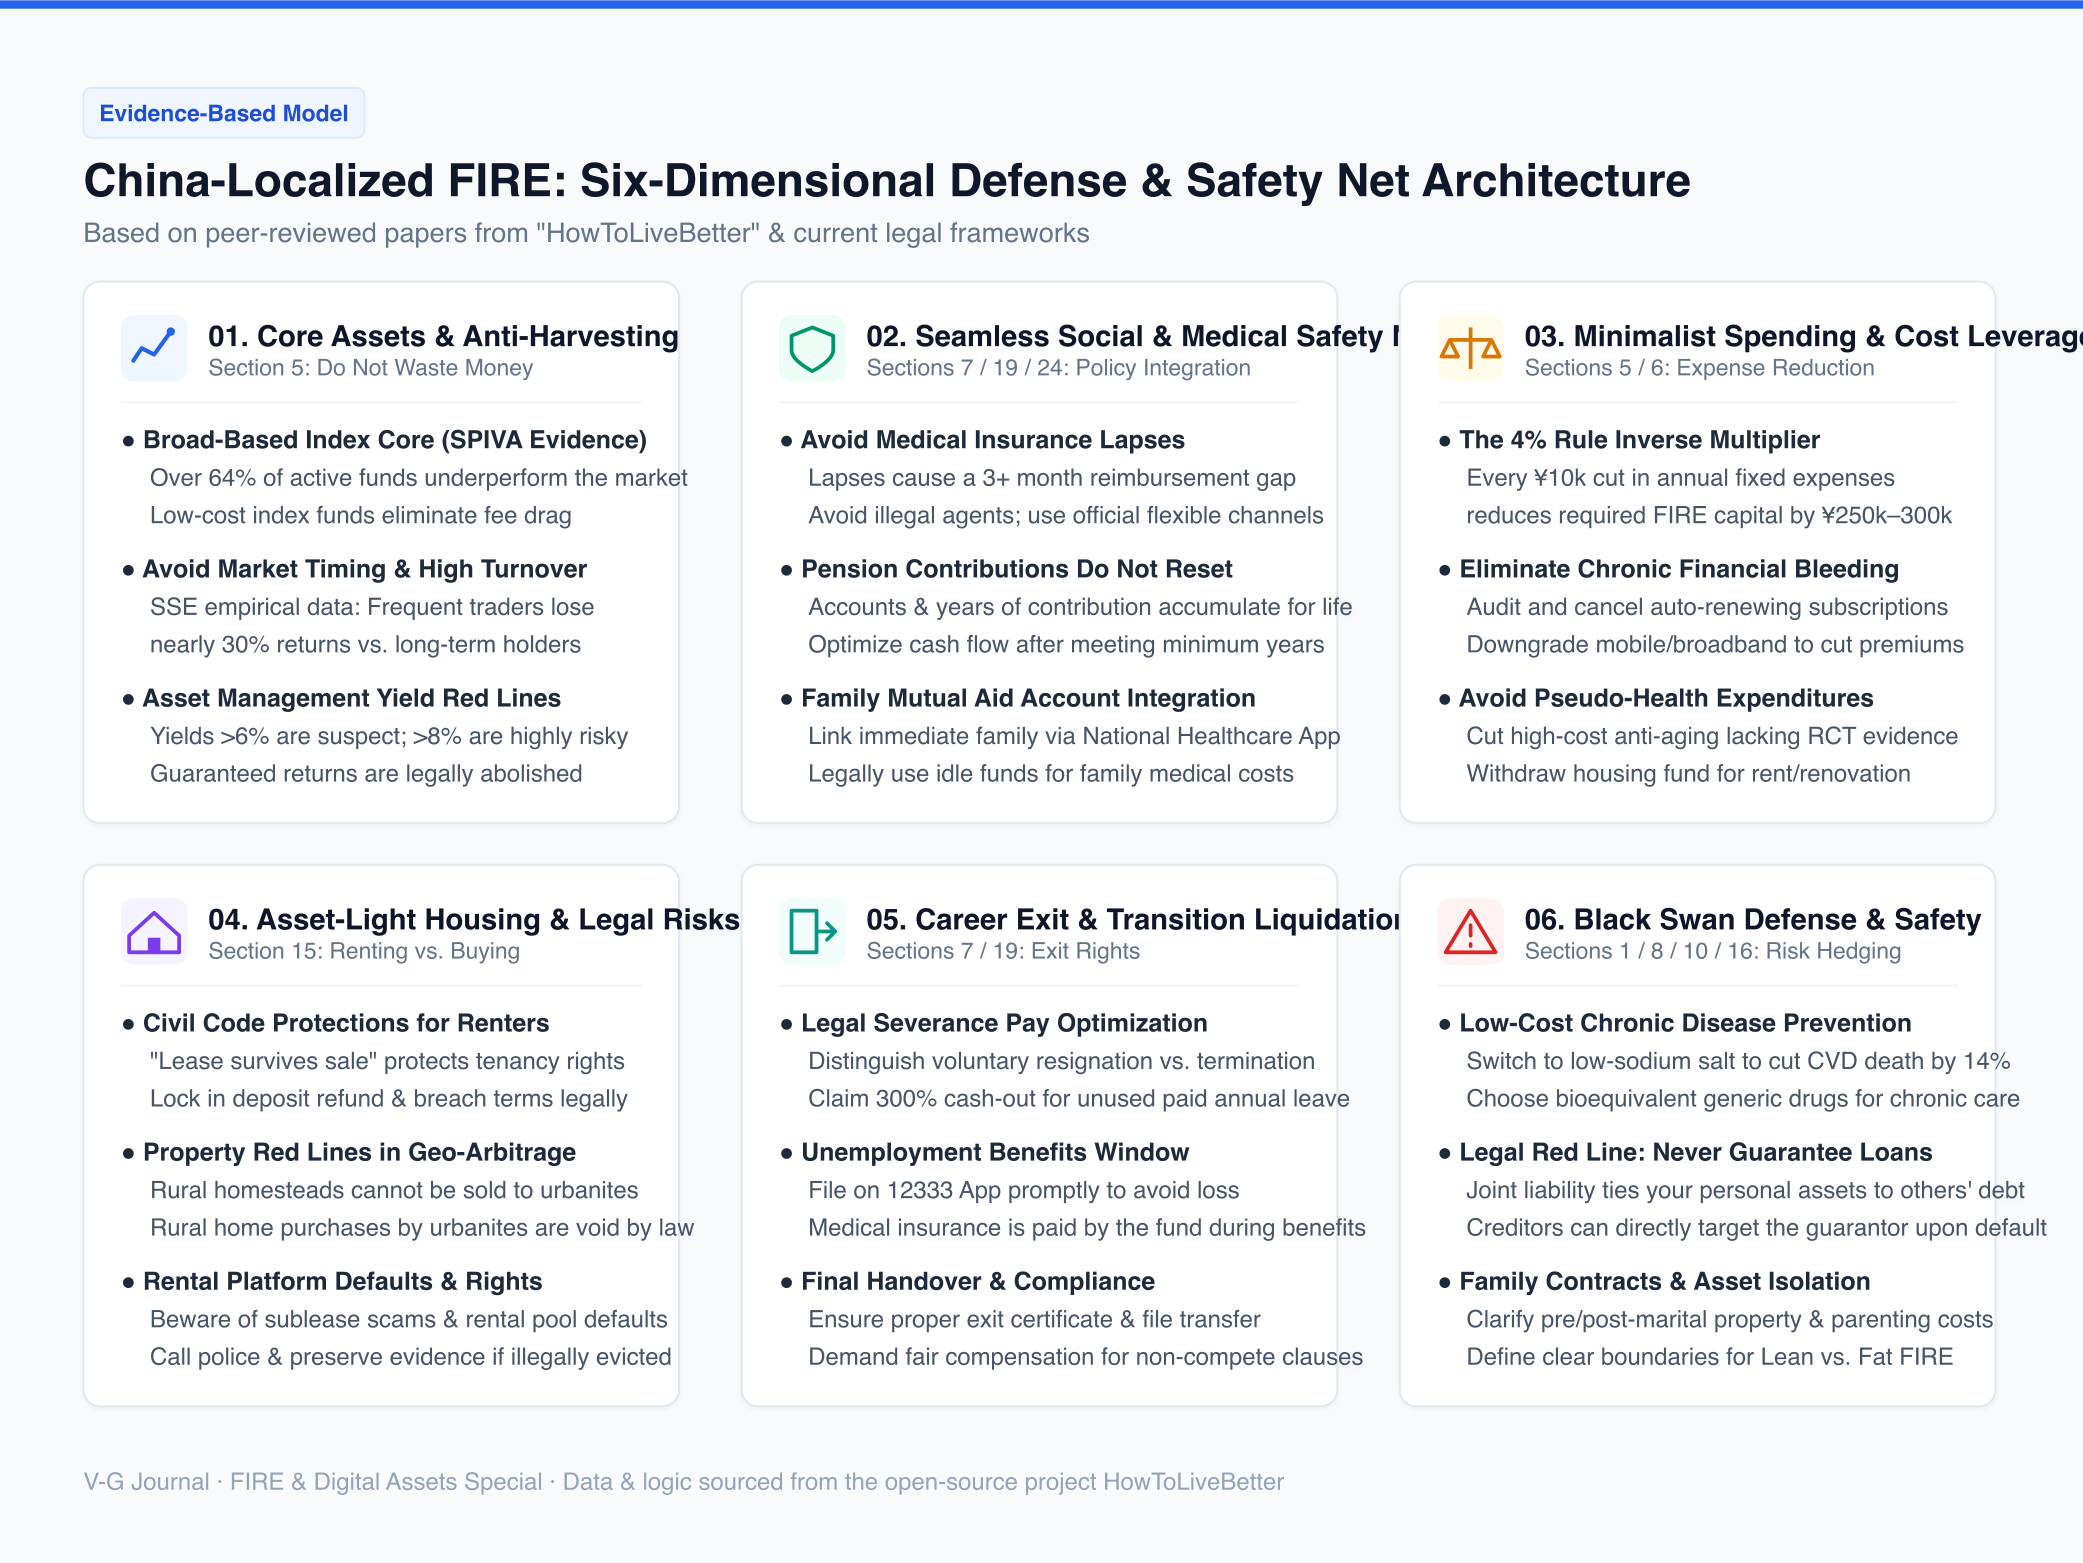
Figure 2: The Six-Dimensional Defense Architecture (Derived from ‘HowToLiveBetter’ legal and academic evidence).
III. The Six-Dimensional Defense Checklist for Localized FIRE
By cross-referencing the guide’s chapters, we can extract six mandatory defensive dimensions for building a personal retirement moat:
Dimension 1: Asset Core & Anti-Harvesting (Section 5)
The core of FIRE is income-generating assets. However, the “urge to accelerate” often leads practitioners into traps.
- Low-Cost Broad-Based Index Funds as the Anchor (5.17)
- Hard Evidence: SPIVA reports show that over 64% of active managers underperform their benchmarks over 20 years. In the A-share market, most active funds fail to beat the benchmark over 3-5 year rolling periods.
- FIRE Insight: High management and custodial fees act as “reverse compound interest,” eating nearly a third of assets over 30 years. Abandon the cult of the “star manager” and anchor to the lowest-fee indices.
- Abstaining from Market Timing and High-Frequency Trading (5.15)
- Hard Evidence: Data from the Shanghai Stock Exchange confirms that the bottom 85% of retail investors lost 250 billion RMB during the 2014-2015 cycle due to frequent trading—a loss equivalent to 30% of their principal compared to a “buy and hold” strategy.
- FIRE Insight: With infinite leisure time, many retirees mistake “full-time trading” for a side hustle. This not only drains attention but statistically leads to significant underperformance.
- Adhering to Regulatory Yield Red Lines (5.6, 5.16)
- Remember the regulatory warning: If the yield exceeds 6%, question it; if it exceeds 8%, it’s dangerous; at 10%, prepare to lose the entire principal. In the post-New Asset Management Regulation era, no legal institution can guarantee principal. For FIRE, avoiding permanent capital loss is infinitely more important than chasing Alpha.
Dimension 2: Post-Employment Social Security Continuity (Sections 7, 19, 24)
The greatest anxiety for early retirees is the gap in social security after leaving a corporate role.
- Never Allow Medical Insurance to Lapse (7, 24)
- Policy Constraint: A lapse in medical insurance triggers a “treatment waiting period” (usually 3+ months) during which the state fund pays zero for hospitalizations.
- Compliance Path: Strictly reject “proxy payment” (guaranteed by third-party agencies), which is legally classified as insurance fraud. Most cities now allow individuals to pay for Flexible Employment Medical Insurance directly via tax apps or government centers.
- The “Non-Zeroing” of Pension Contributions (19)
- Basic pension accounts accumulate interest and years of service. Interruption does not erase previous years. Practitioners should prioritize reaching the minimum 20-year contribution threshold to lock in a lifetime floor, then decide on further contributions based on cash flow.
- Leveraging Family Account Mutual Aid (5.13)
- Before leaving a large firm, medical accounts often have significant balances. Under current policy, these can be linked to parents, spouses, or children via the “National Healthcare Security” App to pay for out-of-pocket outpatient costs, preventing cash flow leakage.
Dimension 3: Lowering the Baseline & Cash Flow Arbitrage (Sections 5, 6)
In the 4% rule, reducing annual spending has a powerful reverse leverage:
Every 10,000 RMB reduction in annual rigid spending lowers the required FIRE principal by 250,000 to 300,000 RMB.
- Excising Invisible Hemorrhaging: Audit all auto-renewals (Apple ID, Alipay, WeChat). Use “Mobile Number Portability” and national broadband speed-up policies to force down communication bills.
- The Negative List (6): Eliminate expensive “anti-aging” supplements and “influencer health checks” (like high-priced PET-CT or pan-cancer gene screening without clinical indications) that lack large-scale RCT validation.
- Liquidating the Housing Provident Fund (5.3): The fund is not just for buying homes. It can be withdrawn for rent or renovations, converting stagnant assets into active cash flow for FIRE operations.
Dimension 4: Asset-Light Living & Legal Red Lines (Section 15)
Many practitioners pursue “geographic arbitrage”—selling in Tier 1 cities to live in lower-cost rural areas. However, a lack of legal literacy can turn this into an asset quagmire.
- Legal Self-Defense for Long-Term Renters (15)
- The “Sale Does Not Break Lease” Principle: Master Article 725 of the Civil Code. If a landlord sells the property, the lease remains valid for the tenant.
- The Fatal Trap of “Rural Retreats” (15)
- The guide is clear: Urban residents are strictly prohibited from purchasing rural homesteads (Zhaijidi) or rural houses. Any private “purchase agreement” with a villager is “void from the beginning” in court. If a policy shift or dispute occurs, your investment and renovation costs are legally unprotected. The only viable path is a long-term lease (capped at 20 years).
Dimension 5: The Professional Exit & Transition Liquidation (Sections 7, 19)
The moment of transition from “employee” to “self-sustained” is the first layer of the safety net.
- Distinguishing Resignation from Negotiated Termination (19)
- Signing a “personal reasons” resignation letter waives statutory severance (N/N+1) and disqualifies you from unemployment benefits.
- Before exiting, demand encashment of unused paid annual leave at 300% of the daily wage rate as per labor law.
- Immediate Filing for Unemployment Benefits (7)
- If you have paid into the system for 1+ year and the termination was not your choice, file immediately.
- The Hidden Perk: While receiving unemployment benefits, the state fund pays your basic medical insurance premiums, allowing you to enjoy full coverage without out-of-pocket costs—a perfect buffer for the early stages of FIRE.
Dimension 6: Black Swan Protection (Sections 1, 2, 8, 10, 16, 18)
The most fragile part of any FIRE plan is its resistance to “Black Swans”—uncontrollable litigation or organ failure.
- Low-Cost Longevity & Chronic Disease Control (1, 16)
- Replace regular salt with low-sodium, high-potassium salt (a high-ROI move; international studies show a 12-14% reduction in all-cause mortality).
- Prioritize “Volume-Based Procurement” (VBP) drugs for hypertension or diabetes (often 50-80% cheaper with strict bioequivalence) to compress lifelong maintenance costs.
- Legal Isolation: The “No Guarantee” Rule (8.7)
- Under the current Civil Code, “signing for a friend” or “guaranteeing for a company” is often presumed to be joint and several liability. If the primary debtor defaults, the creditor can freeze your accounts and seize your property immediately. Never tie your balance sheet to someone else’s business risk.
- The Financial Ledger of Intimacy (10, 18)
- The guide provides a cold economic dissection of marriage and parenting. Marriage is, legally, a joint property contract. Clarifying pre-nuptial assets and the true opportunity cost of childrearing is the fundamental divide between Lean FIRE (minimalist/DINK) and Fat FIRE (high-end retirement with generational trusts).
IV. Conclusion: Common Sense as the Guardrail of Autonomy
In discussions of macro wealth and market cycles, it is easy to get lost in grand narratives. Yet, for the individual, the success of a 30-to-50-year retirement is determined by the most basic common sense and institutional red lines.
The value of HowToLiveBetter lies in its refusal to offer shortcuts to riches or sell vague sentimentality. Instead, it acts as a calibrated vernier caliper, helping those who seek to control their destiny to measure exactly which drains to plug, which holes to weld shut, and which rights to defend.
When you stop paying for illusory active management, stop ignoring the systemic risks of insurance lapses, and refuse to sign lethal legal guarantees, FIRE ceases to be a fragile mathematical hypothesis. It becomes an indestructible reality.
Related Research & Topics
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。