Debt Defusal: A Survival Guide for the 80s Generation
As the 80s generation enters their late 30s and 40s, they face the unique '4-2-1' family burden and the collapse of the growth-era narrative. This guide offers a strategic framework for deleveraging, mitigating single-point failures, and re-engineering personal cash flow in an era of AI-driven disruption.

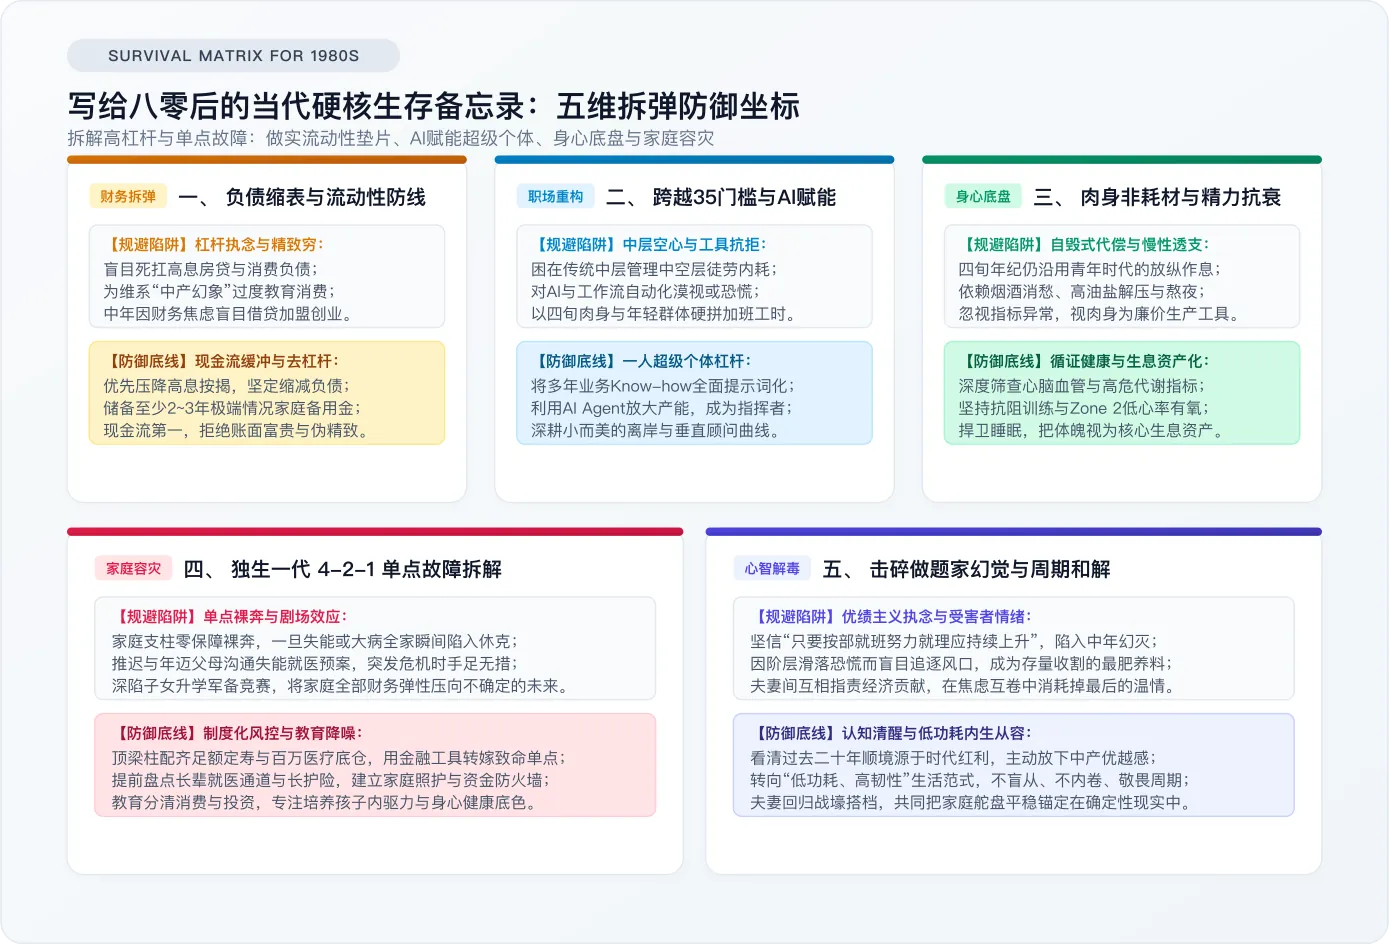
The oldest of the 80s generation have turned forty-six; the youngest are thirty-seven. Everyone has crossed the dreaded “35-year-old threshold” and entered the age of “no longer being perplexed”—or so the traditional narrative goes.
Viewed through the lens of history, the 80s generation is the most dramatically tensioned cohort of the last half-century.
You are the first generation defined by the “only child” policy. Raised in a greenhouse of meritocracy, where one child carried the weight of an entire family’s upward mobility, you became accustomed to the deterministic feedback loop of the “test-taker”: study hard, get into a top university, land a stable job, buy a house, and climb the social ladder step-by-step.
However, this linear narrative—forged during China’s WTO accession and the era of hyper-urbanization—has been ruthlessly rewritten over the past decade:
- The Career Wall: You exited academia only to find the era of guaranteed placement replaced by brutal peer competition.
- The Asset Trap: At the peak of your career-building years, you were swept up by the macroeconomic tide, signing 30-year mortgage contracts at the absolute zenith of asset prices.
- The AI Squeeze: As mid-level career paths narrow due to organizational flattening, the wave of Large Language Models and autonomous agents is eroding the moats of mid-tier cognitive labor.
- The “Single Point of Failure”: You are the structural load-bearing beam for the “4-2-1” pyramid—four aging parents facing health risks, and one or two children caught in an increasingly expensive educational arms race.
With no siblings to share the burden, you and your spouse are the sole pillars. If your career falters or a health crisis strikes, the fragile financial architecture of your household risks catastrophic collapse.
At this stage, true wisdom is not about chasing a “miracle comeback” or high-stakes gambling. It is about abandoning the delusions of meritocracy and performing a cold, surgical defusal of your household balance sheet. Here are five hard truths for navigating the eye of the storm.
I. The Five-Dimensional Defense Matrix
In a cycle defined by tightening liquidity, rapid technological iteration, and an inverted population pyramid, clinging to the strategies of twenty years ago—leveraging up, brute-forcing physical labor, and going it alone—will only accelerate your collapse.
You must construct rigid firewalls across five core dimensions:
| Dimension | The “Test-Taker” Trap | The Hardcore Survival Baseline |
|---|---|---|
| 💰 Financial | Carrying high-interest mortgages; over-consumption to maintain a “middle-class” facade. | Active deleveraging. Prioritize cash flow over book assets. Build a 2-3 year liquidity buffer. |
| 💼 Career | Fighting for mid-level management roles; resisting AI; competing on hours against 20-year-olds. | Tool-based leverage. Become an “AI Super-Individual.” Translate industry know-how into automated workflows. |
| 🩺 Health | Treating the body as a disposable asset; ignoring metabolic warnings. | The primary interest-bearing asset. Prioritize Zone 2 cardio, strength training, and deep sleep. |
| 🛡️ Risk | Bare-bones insurance; ignoring elder-care logistics; over-investing in tutoring. | Risk transfer. Use insurance to hedge against “single-point” failures. Focus on child independence. |
| 🧠 Mindset | Victimhood; internalizing systemic shifts as personal failure. | Low-power resilience. Accept the cycle; treat your spouse as a trench-mate, not a competitor. |
II. Financial Defusal: Ending the “Pseudo-Middle Class” Illusion
The greatest financial error of the 80s generation is mistaking the “paper gains” of the last twenty years for permanent capital.
Many couples leveraged their parents’ life savings between 2017 and 2021 to buy suburban “school district” properties. They maintained a “middle-class” lifestyle—international schools, luxury memberships, and overseas travel—while servicing massive monthly mortgage payments.
In the current era of stagnant growth, asset prices and liquidity have decoupled:
- Paper Wealth is Not Liquidity: When the exit window closes, real estate becomes a cash-flow-draining liability. That mortgage is a Sword of Damocles, stripping you of the bargaining power to walk away from a toxic workplace.
- Passive Deleveraging: If you hold multiple non-core properties with low rental yields, stop waiting for the market to “break even.” Optimize your asset package to unlock cash. If you lack a safe investment yielding over 4%, paying down high-interest debt is the most certain, risk-free return on equity.
- The Cash Buffer: Stop living paycheck to paycheck. Lock away 24–36 months of essential living expenses in high-liquidity, risk-free assets. True luxury is not a brand logo; it is the freedom to say “no” when your employer demands the impossible.
III. Career Breakthrough: Crushing the 35-Year-Old Ceiling
The “managerial test-taker” myth is dead. In the current climate, middle management is the first layer to be scraped away during cost-cutting.
The AI Pivot: Do not view AI as a toy for the young. Your advantage is not your stamina; it is your cross-cycle business intuition.
- Tool-Flow Integration: Stop being a project manager who needs a ten-person team. Use AI to become a “Super-Individual” capable of delivering end-to-end results—from research to product prototyping—alone.
- Micro-Consulting: Build a “second curve” based on your specific industry know-how. Move toward low-friction, offshore-capable delivery models. Even an extra $700/month in independent income provides more psychological security than a hollow corporate title.
IV. Family Disaster Recovery: Solving the 4-2-1 Problem
You are the “load-bearing wall” generation. If you fall, the system collapses.
- Insure the Engine: You and your spouse are the household’s “printing presses.” If you haven’t secured pure term life insurance and comprehensive medical coverage, you are gambling with your family’s existence.
- Institutionalize Elder Care: Do not wait for a crisis. Map out the medical resources, long-term care insurance, and emergency protocols for your parents now. Your greatest constraint is not lack of love, but the physical limit of your time.
- Exit the Education Arms Race: Stop the “theater of anxiety.” The era where a top-tier degree guaranteed a lifetime iron rice bowl is over. Invest in your child’s resilience, curiosity, and problem-solving skills—not in expensive, low-yield tutoring.
V. Mindset: Reconciling with the Cycle
The deepest pain of the 80s generation is the dissonance between your effort and the market’s feedback. You were taught that hard work equals success, but you are now realizing that you were simply riding a massive, once-in-a-century elevator.
The elevator has slowed down. This is not a personal failure; it is a shift in the historical tide.
- Shed the Ego: Accept that you are a player in a macro-cycle. Stop performing “middle-class” status for an audience that doesn’t care.
- Trench-Mate Marriage: When the pressure mounts, the worst thing you can do is turn your spouse into an adversary. Align your financial goals and emotional needs. A household with a unified front is the only true hedge against external volatility.
The meaning of “no longer being perplexed” is not having all the answers. It is the ability to look at the cold, hard reality of the cycle, dismantle the unnecessary risks, and calmly hold your ground. The goal is not to win the game; it is to remain in the game.
Related Research & Topics
The Anatomy of Digital Predation: Inside the Syndicate Targeting the Elderly via Livestream Appraisal Scams
Starlink V4 and the Low-Earth Orbit Satellite Arms Race: How a 100,000-Node Optical Mesh Pierces the Submarine Cable Monopoly
Tello Mobile eSIM
SafetyWing Nomad Insurance
* Disclosure: This post contains affiliate links. If you make a purchase through these links, V-G Journal may earn a small commission at no additional cost to you. We only recommend services we independently evaluate and trust.
FIRE and Golf:自由旅居之路
专注于为追求 FIRE 与品质生活的人群提供特惠打球权益与候鸟微度假。不持一砖一瓦,运营品质生活。